









Call us
Call us
 FOR EXISTING POLICY
Have query on premium, payout or any servicing need?
Call us:
 FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY (NRIs)
Note: Consent is provided to Tata AIA Life Insurance Company Limited to contact you by calling/giving missed call to the above numbers.
Thank you for sharing your details. To receive a call from Tata AIA Financial Advisor.
reCAPTCHA is not working.
No relevant search results found.
Popular searches
Continue from where you left of
Life insurance provides financial protection to the beneficiary during the policy term. The death benefit helps the family... Read more manage essential expenses in the absence of the policyholder.
In addition to life cover, many policies also support long-term financial goals. These may include buying a house, funding a child’s education, or planning for retirement. Read less

Have questions?
By submitting details, I accept TATA AIA Life’s Privacy Policy. TATA AIA Life Insurance Co. Ltd will send you updates on your policy, new products & services, insurance solutions or related information. Select here to opt-in.
Kindly enter the OTP sent to
Please enter valid OTP
01:60
Didn't receive OTP?
Success
Your details have been successfully submitted. A representative from Tata AIA Life Insurance will call you soon.
Failure
Your details could not be saved.
Please try again.
Your details have been successfully submitted. A representative from Tata AIA Life Insurance will call you soon.
There was some error in submitting details please try again
Protect the financial security of your loved ones with our affordable term insurance plans.
Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN:110N176V12)
Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN: 110N171V15)
Grow your wealth with our guaranteed return plans for a fikar-free future and also save tax9 up to ₹46,80024.
Non-Linked, Non-Participating, Individual Life Insurance Savings Plan (UIN: 110N158V14) | 27T&C apply
27Premium excluding taxes for age group of 18 to 50, Male/Female, Standard life, Plan Option 1 (Regular Income), Premium Payment Term 10 years, Policy term 15 years, Income term 30 years. Income will start from 16th year. Total Guaranteed Benefit: ₹46,06,600
Individual, non-linked, participating, Life Insurance Savings Plan (UIN: 110N207V03)
Individual, Non-Linked, Non-participating, Life Insurance Savings Plan (UIN110N163V14)
9Life cover: ₹10 Lakh | Male age 35 Years | Non-Smoker | Policy Term: 37 Years | Premium Payment Terms: 12 Years | Return of premium at the end of Policy term ₹13.2 Lakh
Solution CompositionOur comprehensive plan takes care of your health, wellness, and financial security all in one.
In This Policy, The Investment Risk in Investment Portfolio Is Borne by The Policyholder
Plan your retirement wisely with a suitable pension plan for peace of mind in your golden years
Non-Participating, Unit Linked, Individual Life Insurance Pension Plan (UIN: 110L182V09)
A Non-Linked, Non-Participating, Annuity Plan
(UIN:110N1761V13) | 25T&C apply
A life insurance policy is a contract between an individual and an insurance company that provides financial protection to the policyholder’s nominee or beneficiaries, subject to the policy terms. In return, the policyholder pays premiums at the agreed frequency to maintain the coverage.
If the insured person passes away while the policy is active, the insurer pays the applicable death benefit to the nominee. Depending on the type of life insurance plan, the policy may also offer maturity benefits, savings, market-linked15 investment opportunities or retirement income.
The purpose of life insurance varies according to an individual’s financial responsibilities and long-term goals. Understanding the available life insurance plans can help individuals compare protection, savings and investment features before selecting a policy that suits their requirements.
Different life insurance plans address different financial needs. Some focus on protecting dependants, while others combine life cover with savings, investment opportunities or retirement planning. The following categories explain their key features and the needs they may address.
Term insurance provides life cover for a specified period. If the insured person passes away during the policy term, the nominee receives the applicable death benefit, subject to policy conditions. These plans primarily focus on financial protection and may suit individuals who want to provide for dependents, cover outstanding loans or replace lost household income.
Savings plans combine life insurance with a structured savings approach. Depending on the product, they may offer a maturity benefit, periodic payouts or other policy benefits. These plans may suit individuals planning for future expenses, such as education, family milestones or major purchases. Benefits and payout conditions vary by policy.
Wealth-oriented life insurance plans, including Unit Linked Insurance Plans (ULIPs), combine life cover with market-linked15 investments. A portion of the premium goes towards insurance charges and related costs, while the remaining amount is allocated according to the plan’s investment structure. These plans may suit individuals with long-term financial goals who understand market fluctuations and investment risk.
Retirement plans help individuals prepare financially for the period after they stop earning a regular salary. Depending on the product, they may support corpus accumulation, pension benefits or regular income during retirement. These plans may be relevant to individuals who want to account for living expenses and other financial commitments in their later years.
Group life insurance provides coverage to multiple individuals under a single policy, commonly arranged by employers, organisations or associations. It can offer financial protection to employees or eligible members and their nominees. Coverage amounts, eligibility, exclusions and policy duration depend on the group arrangement.
Endowment plans combine life cover with a savings component. If the insured person survives until the policy maturity date, the insurer pays the applicable maturity benefit. If the insured person passes away during the policy term, the nominee receives the benefit specified in the contract. These plans may suit individuals seeking protection alongside a structured savings arrangement.
A non-linked participating endowment plan combines life insurance with participation in the insurer’s eligible surplus. Depending on the policy, bonuses may be declared in addition to the benefits specified in the contract. Bonus amounts and eligibility depend on the insurer’s declarations and policy conditions, so they should not be treated as guaranteed unless stated.
Child plans are designed to support financial goals related to a child’s future, including higher education and other major milestones. Depending on the policy, they may combine life cover with savings and scheduled payouts. Some plans also include provisions that support the child’s financial goals if the insured parent passes away during the policy term.
Money-back plans provide life cover along with periodic payouts during the policy term. A portion of the policy benefits may be paid at specified intervals, with any remaining benefit payable according to the contract. These plans may suit individuals who want access to scheduled payouts for planned expenses rather than receiving all applicable benefits at maturity.
Capital guarantee plans combine life insurance with an investment structure designed to protect a specified amount, subject to the policy terms. Depending on the product, a portion of the premium may be allocated to market-linked15 funds. Individuals should review the guaranteed11 amount, charges, exclusions and conditions carefully to understand precisely what the plan protects.
Whole life insurance plans provide coverage for an extended period, potentially up to a specified advanced age or for the insured person’s lifetime, depending on the contract. The applicable death benefit is paid to the nominee if the insured person passes away while the policy remains in force. These plans may suit individuals seeking long-term financial protection for their beneficiaries.
Annuity plans are designed to provide income during retirement. Depending on the options selected, the policyholder may pay a single premium or make contributions over a specified period. Income payments may begin immediately or after a deferment period. The payment frequency, amount and duration depend on the annuity option and policy conditions.
Life insurance operates through a simple process where the policyholder pays premiums and receives insurance protection for the chosen policy term. In exchange, the insurer agrees to provide policy benefits when specified events occur according to the policy conditions.
The process begins when an individual selects a suitable life insurance. During application, information such as age, health history, occupation, lifestyle habits, and required coverage amount is provided to the insurer.
After evaluating the application, the insurer determines the premium amount and issues the policy.
For example, Ankit purchases a life insurance policy with a coverage amount of ₹75 lakh and a policy term of 25 years.
Once the policy becomes active, the policyholder pays premiums according to the selected frequency, such as monthly, quarterly, half-yearly, or annually.
The premium amount helps maintain policy coverage throughout the selected term.
Different life insurance work differently:
In a term insurance plan, premiums provide pure life cover during the selected period.
In an endowment plan, premiums contribute towards both insurance protection and savings accumulation.
In a money-back plan, policy benefits may be distributed at specified intervals during the policy term.
In market-linked15 plans, a portion of the premium provides insurance coverage, while another portion is invested in selected funds.
If the insured person passes away during the policy term, the nominee can submit a claim along with the required documents. After claim verification, the insurer pays the applicable death benefit according to policy conditions.
For instance, if Ankit passes away during the policy term, the nominee may receive the policy benefits specified under the contract.
In plans that include maturity benefits, the policyholder receives the maturity amount if they survive until the end of the policy term. The amount payable depends on the selected policy structure and applicable benefits.
Life insurance can support a family’s financial planning by providing protection against the loss of an earning member. Depending on the product, it may also help with savings, retirement preparation, and other long-term requirements.
Before choosing a policy, it is useful to understand the benefits it may offer and the conditions attached to them. Features vary across term, savings, investment-linked and retirement-oriented products.
The death benefit is the amount payable to the nominee or beneficiary when the insured person passes away under circumstances covered by the policy. The payout is determined by the contract and may help dependants meet living expenses, liabilities and other financial commitments.
Some life insurance policies pay a maturity benefit if the insured person survives until the end of the policy term. The amount depends on the product structure and applicable benefits. Pure term insurance generally does not provide a maturity payout unless a return-of-premium feature is included.
Riders16 are additional benefits that may be attached to an eligible life insurance policy for an extra premium. Depending on availability, these may cover specified critical illnesses, accidental death, disability or waiver of premium. Each rider16 has its own eligibility criteria, exclusions and claim conditions.
Depending on the policy, premiums may be payable throughout the policy term, for a limited period or as a single payment. The selected payment option affects the timing of premium obligations, while the duration of life cover is governed by the policy contract.
The table below outlines how a life insurance policy can benefit individuals at different stages of life.
| Age Group | How Life Insurance Helps |
|---|---|
| 20-30 Years | Young professionals can benefit from lower premiums while enjoying comprehensive coverage. This may help protect themselves and their families, and might also cover expenses like educational loans. |
| 30-40 Years | A life insurance policy secures the financial future of your spouse, children, and extended family. It also helps cover liabilities such as home loans and vehicle loans, reducing financial stress. |
| 40-50 Years | Life insurance in this age group helps you begin retirement planning and save for major expenses, like funding your children’s further education, and ensuring long-term financial stability. |
| 50 Years and Above | For those over 50, life insurance provides either a lump sum payment or regular income. This helps cover daily expenses and ensures financial security during retirement for a peaceful life.. |
Apart from the age groups mentioned above, the following people can also benefit from a life insurance plan:
Here’s a quick comparison of the different types of life insurance plans and their coverage amount:
| Type of Life Insurance Policy | Overview | Purpose | Who Should Consider Buying This Policy? | Popular Tata AIA Plans | Coverage | Maturity Benefits | Death Benefits |
|---|---|---|---|---|---|---|---|
| Term Life Insurance Plan | Affordable plan that provides financial protection to your family | Pure risk cover Whole life cover |
Sole earning members of a family, young professionals, family members, and business owners | Tata AIA Sampoorna Raksha Promise |
Pure risk cover | No maturity benefits | Offers death benefits |
| Savings Insurance Plan | Offers life cover and guaranteed returns for future financial goals. | Life cover Guaranteed maturity benefits 8T&C apply |
Newly married couples, young parents, and young professionals | Tata AIA Fortune Guarantee Plus |
Insurance cover+ savings | Offers maturity benefit | Offers death benefits |
| Unit-Linked Insurance Plan | Policyholders invest in funds (equity, debt, hybrid). ULIP has lock-in period of 5 years for partial withdrawal | Life cover Market-linked returns17 |
Young professionals, newly married couples, and young parents | Param Rakshak Life Pro + | Insurance Cover + Market-linked Investment Benefits | Offers maturity benefit | Offers death benefits |
| Retirement Plan | Ensures regular income and financial independence during post-retirement years. | Life cover Annuity benefits |
Family members, individuals planning early retirement, and individuals having dependent family members throughout life | Tata AIA Fortune Guarantee Pension |
Insurance Cover + Saving | maturity benefits | death benefits |
Life insurance plays a vital role in securing your financial future and protecting your loved ones. As your responsibilities grow and change over time, the need for life insurance evolves with each life stage.
The following section explains the Do’s and don’ts while buying a life insurance plan:
The cost of life insurance depends on factors such as age, health, coverage amount, policy term and product type. Comparing these details with your financial needs can help you assess affordability and understand what the premium pays for before you buy a life insurance policy.
The amount of life cover you need varies at different stages of life. It’s important to ensure your policy provides an adequate amount of coverage by factoring in your financial goals, obligations, and liabilities to safeguard yourself and your family’s future.
With fewer responsibilities and a steady source of income, you may opt for a sum assured that is ten times your annual income and liabilities. Such a policy will help you protect your family and offset the impact of inflation.
This stage often involves marriage, children, and increasing financial responsibilities. Therefore, it is essential to consider your income, expenses, future financial goals and other outstanding loans and liabilities. Also, factor in inflation to determine adequate life insurance coverage that safeguards your family’s long-term financial well-being.
At this stage, while supporting your grown-up but financially dependent children, it's also crucial to begin planning for your retirement. Ensure that your life insurance coverage is adequate for your requirements.
After retirement, if you have family members who will remain financially dependent throughout their life, ensure adequate coverage to secure their financial needs to sustain a life in your absence.
To minimise the risk of your life insurance claim being rejected, it’s important to follow a few key steps:
Always disclose correct details about your age, occupation, lifestyle habits (like smoking or drinking), income, and medical history. Misrepresentation can lead to claim denial.
Be transparent about any pre-existing medical conditions, surgeries, or family health issues. Non-disclosure may result in rejection.
Fill out the proposal form yourself to ensure all information provided is true and accurate.
Keep your nominee information updated, especially after significant life changes like marriage or the loss of a nominee.
Ensure timely premium payments to keep your policy active. A lapsed policy will not provide benefits.
File your claim as soon as possible after the incident. Delays can complicate the process.
Opt for an insurer with a strong claim settlement record to improve your chances of claim approval.
Understanding common policy terms makes it easier to compare benefits, premiums, and coverage conditions. These are the key definitions to know before purchasing or managing a policy.
A policy is the insurance contract issued by the insurer. It records the coverage, benefits, exclusions, premium obligations and conditions that apply to the agreement.
The sum assured is the amount specified in the policy as the insured benefit, subject to the contract’s terms. The amount payable may vary according to the benefit structure and whether the claim relates to death, maturity or another insured event.
The annualised premium is the premium calculated on a yearly basis for the policy. It generally excludes applicable taxes, additional premiums and underwriting-related loadings, where relevant.
The coverage period is the duration during which the policy provides insurance protection, provided the policy remains active and its conditions are met.
The maturity date is the date on which a policy with maturity benefits reaches the end of its specified term. The benefit, if any, is payable according to the contract.
A life insurance premium is the amount paid to the insurer in exchange for the benefits and coverage described in the policy. The amount depends on factors such as age, health, coverage, policy duration and product type.
Premium payment frequency refers to how often premiums are paid, such as monthly, quarterly, half-yearly or annually. The payment term describes how long premiums are payable, for example, throughout the policy term, for a limited period or as a single payment.
Life insurance riders16 are optional benefits that can extend coverage for specified events, subject to availability and eligibility. They may require an additional premium and have separate exclusions, waiting periods or claim conditions.
22T&C apply.
Understanding how a life insurance policy works is key to making an informed decision. Here's a simplified overview in three steps:
Start by choosing a life insurance plan that matches your financial needs and long-term goals. Consider the required life cover, your budget for premiums, and any additional benefits you might need. Tools like a term insurance calculator can help you estimate premiums. You can also enhance your plan with riders29, such as critical illness or accidental death coverage.
Once your plan is in place, pay your premiums regularly, monthly, quarterly, half-yearly, or annually, based on the frequency you select. The premium amount will depend on factors like age, health, coverage amount, and policy term. Timely payments are essential to keep your policy active and ensure continued protection.
If the insured person passes away during the policy term, the nominee can file a claim. Submitting the required documents promptly online, via email, or at a branch helps in faster claim settlement.
The premium payable on your life insurance policy is calculated based on the following factors.
As you age, your body becomes more prone to many age-related health issues. Due to this, you will have to pay higher premiums for greater risk. Hence, buying a life insurance policy at a young age means lower premiums.
The life expectancy of women is longer than that of men. Therefore, most life cover insurance plans have a provision where women policyholders can avail of special premium rates as compared to men policyholders. Hence, your gender will play an essential role in the calculation of your life insurance premiums.
If you have smoking or heavy drinking habits, you are at a greater risk of many diseases and conditions than someone who doesn’t drink or smoke. Your insurer will consider this factor when deciding the premiums for your policy.
If your life insurance plan has a longer policy tenure, you will be paying premiums for a greater number of years. It makes life insurance more expensive than paying for a short-term life insurance policy for a limited term.
If you have any pre-existing health conditions as diagnosed by a medical professional, you will need to pay higher premiums. Additionally, you may also have to go through a waiting period before receiving any policy benefits.
If you or your family have been diagnosed with any critical illnesses in the past, it is a cause for concern. Insurers consider this factor while calculating the premiums since there may be a potential risk of a critical illness in the future.
Tax6 benefits on life insurance depend on the policy type, premium amount, issue date and applicable tax regime. From 1 April 2026, the Income-tax Act, 2025, replaces the Income-tax Act, 1961, for the updated tax framework. Therefore, taxpayers need to refer to the provisions applicable to the relevant tax year when assessing deductions on premiums and exemptions on policy proceeds.
Under the earlier Income-tax Act, 1961, eligible life insurance premiums qualified for a deduction6 under Section 80C when an individual opted for the old tax regime. The combined annual deduction6 limit was ₹1.5 lakh across eligible investments and payments, subject to the prescribed conditions. This deduction was not available under the new tax regime.
For tax years beginning on or after 1 April 2026, the corresponding provisions under the Income-tax Act, 2025 apply. The applicable deduction6 and eligibility conditions should be verified against the updated law and the taxpayer’s chosen tax regime.Section 10 (10D)
Under the earlier Section 10(10D) of the Income Tax Act, 1961, qualifying life insurance proceeds could be exempt from tax6, subject to specific conditions. These included rules relating to the premium-to-sum-assured ratio, policy issue date and aggregate premium thresholds for certain ULIPs and non-ULIP policies.
The updated Income-tax Act, 2025 framework applies from 1 April 2026. Readers should refer to its relevant provisions for the applicable tax year rather than assuming that the earlier section number and every previous condition remain unchanged. Death benefits and maturity or surrender proceeds may receive different tax6 treatment depending on the applicable provisions and policy details.
Tax6 treatment depends on individual circumstances. Consult a qualified tax professional.
Here are the key steps to follow when buying term insurance online:
Visit the insurer's website and provide personal details like contact information, date of birth, gender, and income details.
Choose a suitable policy tenure and sum assured based on your age and financial needs. A longer tenure is advisable for younger individuals, while middle-aged individuals may prefer a shorter term.
Pick the preferred premium payment option (monthly, quarterly, bi-annually, or annually) and the payment term (regular, limited, or single premium).
Choose a lump sum payout, a combination of lump sum and regular monthly income, or a monthly income for a specific period.
Enhance coverage by adding riders29, like critical illness or accidental death riders.
Complete KYC by providing necessary documents, and provide medical history if required.
Read the terms and conditions carefully, then proceed to the payment gateway to complete the purchase. A policy document will be emailed to you.
When purchasing a term life insurance policy online, you will need to submit various documents to complete the process. These documents help the insurer assess your eligibility, calculate your premiums, and verify your information. Below are some of the key documents required for buying term insurance, which may be required during the policy purchase.
Salary slips, ITRs, bank statements, Form 16 etc.
Aadhaar card, passport, driving license, voter ID.
PAN card, passport, or birth certificate.
Recent passport-sized photo.
Details of health conditions and pre-existing diseases (if applicable).
Information on current life insurance policies.
Life insurance is a vital financial tool that provides numerous benefits for securing your future and that of your loved ones. It offers protection against uncertainties, ensures long-term financial stability, and supports various financial goals. Here’s why you should consider buying life insurance:
A life insurance plan offers financial protection that secures the financial future of your family in the event of your unexpected demise. The death benefit may be utilised to pay for their routine expenses, clear off debts, and plan for their future financial commitments.
A life insurance rider29 can cover you for both minor and major critical illnesses, helping you avoid treatment costs while keeping your basic coverage intact.
With the increase in age, your premium amount may increase. If you purchase a life insurance policy at an early age, you can benefit from low premiums that let you enjoy high coverage.
With a life insurance savings policy, you can save funds for a maturity benefit to create a plan for your beneficiaries during uncertain times. It also allocates your funds in a safe avenue that can get you assured returns later.
A life insurance wealth solution can help you invest and accumulate your wealth from market-linked returns30 over the years while also securing your family with a life insurance cover. Thus, a single life insurance plan provides the dual benefit of investment and life cover.
When you have a life cover insurance policy, apart from protecting your family, you can also use the maturity benefits it offers for your retirement years. And in case of your untimely demise, your family can sustain itself financially.
Under Section 80C of the Income Tax Act, the life insurance premiums paid towards a policy are eligible for tax7 deductions. You may claim up to a maximum of ₹1.5 Lakh on these premiums for a given financial year. Further, the life insurance payouts also qualify for a tax7 exemption under Section 10(10D) of the Income Tax Act.
With life insurance coverage safeguarding your family from life’s uncertainties, you can have peace of mind, knowing their financial future is secure, even in the most challenging times.
Life insurance is an essential financial tool that offers women both protection and investment benefits, making it a smart choice for long-term financial planning.
Women generally have lower risk profiles, leading to cost-effective life insurance premiums.
Provides a financial cushion during emergencies or loss of income due to illness.
Helps build funds for goals like education, marriage, or retirement.
Under Section 80C, premiums qualify for deductions up to ₹1.5 lakhs.
Supports regular expenses in case of unforeseen events.
Offers added protection during major health issues.
Our experts are happy to help you
Our experts are happy to help you!
The payout options under a life insurance plan can be quite flexible, and you can choose the payout as per your needs and convenience.
Under life insurance, you can choose to receive the payout or sum assured as a lump sum. This means a single, one-time payout will be made to you or your nominee. This can be either as a maturity benefit or a death benefit, respectively.
The regular income benefit pays out the policy benefits as a regular income to the policyholder. This begins from a certain point in the policy term or after the policy term, for a specified period based on the policy terms and conditions.
Some life insurance plans offer the sum assured of the policy as a combination of a lump sum payout and regular payouts. These payouts are provided for a specified number of years or the income period, as per the policy guidelines.
Finding the best life insurance plan involves more than just comparing premiums. It requires a thorough understanding of your personal financial goals, future responsibilities, and the type of coverage your family would need in your absence. By evaluating your current situation and using available tools, you can choose a plan that offers the right balance of protection, affordability, and long-term value. Here’s how to find the best life insurance plan.
Purchasing a life cover insurance policy online can offer a host of benefits that outperform the benefits of buying it offline. While the insurance plans do not change in any way, here is how the online purchase can make the process more convenient and smoother:
Right from features of a life insurance plan to its premiums, reviews and the insurer’s claim settlement ratio, all details are at your fingertips, which makes it easier for you to make an informed choice with no hidden information.
Online insurance plans enable you to compare life insurance plans while saving a whole lot of time. With the help of our online life insurance premium calculator, you can simply calculate your premiums and compare the plans.
When you buy life insurance online, you can save a lot of funds as compared to purchasing it offline. In addition, you can benefit from discounts on premium rates while choosing the digital payment options.
When buying an online life insurance plan, secure online payment options can save you a lot of time during the payment process. This process also makes it easier for you to make the transactions when you need to claim tax7 deductions.
| Factors to consider | General Insurance | Life Insurance | Health Insurance |
|---|---|---|---|
| Coverage | For non-life assets, including motor insurance, travel insurance, etc. | For life cover | For health-related treatments |
| Premium payment frequency | At inception and during renewals | Single payment or regular payments for a limited term or the entire policy tenure | At inception and during renewals |
| Payouts | Cashless claims Reimbursement claims |
Lump sum Regular income Combination of both |
Cashless claims expenses Reimbursement claims |
| Policy tenure | Short term | Long term | Short term |
| Claims | At applicable insured events | Death claim Maturity claim Rider29 claim for health-related treatments and procedures |
For health-related emergencies and treatments. |
Frequently Asked Questions
1.What is a life insurance policy?
A life insurance policy is defined as a contract between the insurance provider and the policyholder, where the insurer promises to pay a specified sum to the beneficiaries upon the death of the insured person or after the policy reaches maturity. The policyholder must, however, pay premiums regularly to ensure the policy remains active.
2.What are the types of life insurance plans?
The different types of best policy for life insurance in India are:
● Term Plans: Term insurance plans are flexible and offer a simple but extensive life insurance coverage along with a death benefit.
● ULIPs: Unit-Linked Insurance Plans combine investment and life insurance coverage to offer market-linked13 returns and life cover protection.
● Savings Plans: Savings plans offer an opportunity to create long-term savings so that you can create a savings fund and also enjoy life insurance coverage.
● Retirement Plans: Retirement plans help you benefit from accumulated savings that offer assured returns in the form of a lumpsum or regular income during retirement.
● Group Plans: Group insurance plans offer insurance coverage to members of a group, such as employees of an organisation, under a single life insurance policy.
● Combo Plans: Combo plans are a combination of two or more life insurance plans and riders that create a comprehensive life insurance solution for the policyholder.
3.How to choose a life insurance policy for my family?
To choose a life insurance policy for your family, ensure that the sum assured is sufficient for their future financial needs. Take into account your current income, your ongoing financial obligations, all outstanding liabilities such as loans and debts, as well as potential medical emergencies, while selecting an adequate life insurance policy coverage for your family.
4.Is it more convenient to purchase life insurance online?
Yes, purchasing life insurance online can be much more convenient since you can easily calculate premiums online, carry out all the research, read online reviews, check the individual death claim settlement ratio of your insurer, and make the purchase and payment from anywhere and at any time.
5.Can a life insurance policy cover an individual who smokes?
Yes, smokers can be covered under a life insurance policy. However, due to higher health risks associated with smoking, insurers typically charge higher premiums compared to non-smokers.
6.What do you mean by paid-up value in life insurance?
Paid-up value is the reduced coverage amount a policyholder receives when premium payments are discontinued after a certain minimum period. The policy stays active with lower benefits, calculated based on premiums paid and the original sum assured.
7.Can life insurance policies be used as tax-saving options in India?
Yes, life insurance policies are eligible for tax9 benefits. However, the primary aim of a life insurance policy is to offer life cover and should not be used only as a tax-saving option.
8.Are life insurance payouts subject to taxes?
Life insurance payouts are generally not taxable. Under Section 10(10D) of the Income Tax Act, maturity and death benefits are tax-exempt9, provided certain conditions are met, such as compliance with premium payment limits and policy terms.
1.What is the main purpose of life insurance plans?
The main purpose of life insurance is to financially secure the family or dependents of the policyholder after their death. During the policy term, the dependents are covered under the policy. If the policyholder passes away within the policy term, the death benefit or sum assured will be paid out to the beneficiaries, helping them maintain their financial stability.
2.Why is life insurance important in India?
Life insurance is crucial in India because many families rely on a single earning member or a single source of income. In the event of the sole breadwinner's untimely death, the loss of income can cause significant financial strains for the family. Relying on emergency savings during such times may not be sustainable. Since life insurance plans are designed to provide a death benefit sum assured to the family upon the policyholder’s death, life insurance plays a vital role in ensuring financial stability.
3.What types of policies does Tata AIA Life Insurance offer?
Tata AIA Life Insurance offers:
● Term Plans
● Savings Plans
● Unit Linked Insurance Plans
● Money-Back Plans
● Retirement Plans
● Group Insurance Plans
● Combo Plans
4.Which are the popular term insurance policies sold by Tata AIA Life Insurance?
The various Term Insurance policies offered by Tata AIA Life Insurance are:
● Tata AIA Sampoorna Raksha Promise
● Tata AIA Maha Raksha Supreme Select
5.What is the difference between whole life and term life insurance?
The primary distinction between whole life and term life insurance is that whole life insurance, as the name implies, offers coverage for the entire lifetime of the policyholder. On the other hand, term insurance provides coverage for a specific period or a set number of years, as determined by the policyholder.
6.Which is better whole life insurance or term life?
The decision between whole life insurance and term life insurance depends on the requirements of the policyholder and their family. If you seek coverage for a specific term or up to 40 years, term insurance is an excellent choice, offering a higher sum assured with lower premiums.
On the other hand, a whole life insurance policy is ideal for those who wish to provide lifetime coverage for their family without the need to purchase a new policy. This policy ensures coverage until the policyholder reaches 100 years or for their entire life.
7.What is the difference between savings plans and Unit-Linked Insurance Plans?
Unit-Linked Insurance Plans (ULIPs) invest a portion of the premiums in market-linked funds19, meaning the returns are subject to market fluctuations but are not guaranteed. On the other hand, savings plans help you accumulate wealth in low-risk avenues over time and offer guaranteed returns at the end of the policy term.
8.What is the best age to get life insurance?
One should purchase life insurance early to benefit from lower premiums. Although it is possible to get a life insurance plan later in life, policy premiums will be higher as older age is associated with increased health risks. When you are young, the risk of health issues is lower, which results in lower premiums.
9.Is it too late to get life insurance at 50 years of age?
Though it is advisable to purchase life insurance as early as you can, you can still avail of a new life insurance policy at the age of 50 years. However, given the higher age of the insured, the policy premiums will also be higher due to the risk of health conditions.
10.What is the minimum & maximum age to buy life insurance?
For most life insurance policies, the minimum entry age for buying life insurance is 18 years, while the maximum entry age could be between 65-75 years and may vary across different policies.
11.When should I buy a life insurance policy?
You can purchase life insurance at any stage of your life when you feel that you have upcoming financial responsibilities. It is also important to consider why you should buy life insurance. For instance, if you are the sole earning member of your family, a life insurance policy will ensure a financial backup for your beneficiaries in the event of your untimely death, which will lead to a loss of income. Most people purchase life insurance policy plans early in life to benefit from lower policy premiums.
12.Who Should Buy a Life Insurance Plan?
Here’s who can buy life insurance.
●Young Adults: As a young adult, one should have a life insurance policy so that they can prepare for future financial responsibilities and avail of lower policy premiums. Even though the current situation may not need life insurance protection, a young individual should plan for their future.
●New Families: Newly married couples or new parents should avail of a life insurance policy since they may have one or more dependents such as aged parents and/or young children. Since the financial obligations are greater, life insurance can help protect your family in case of a misfortune.
●People with Home Loans: If you have purchased a new home and are paying off the EMIs along with others bills, a life insurance policy can help you safeguard your family from these financial obligations in your absence. The sum assured of the policy can assist your loved ones in paying off any pending loans and debts.
●Business Owners: People who have just started their own business or are growing their venture should get life insurance plans. This is because losses to the business in your absence can impact your family. In such a situation, your life insurance policy can help safeguard your family and your business.
13.Do you get your amount back at the end of the term life insurance?
If you have a level term life insurance policy, you will not get any maturity benefits since the coverage will expire at the end of the policy term. In this case, only if the policyholder passes away during the policy term, the death benefit will be paid out to their beneficiaries.
Term plans with return of premiums, however, do offer the total premiums paid as a return at the end of the policy term. If the policyholder survives the policy term, they can get the maturity benefit.
14.Does life insurance offer tax benefits?
Most life insurance plans offer the following tax7 benefits:
●Under Section 80C of the Income Tax Act, the policy premiums paid for the life insurance policy qualify for tax deductions.
●The death benefits offered by the life insurance policy are exempt from taxes under Section 10(10D) of the Income Tax Act.
●Health rider premiums, if any, paid towards the life insurance plan qualify for tax deductions under Section 80D of the Income Tax Act.
15.Do I need to pay taxes on the maturity benefits of my life insurance policy?
Maturity benefits from a life insurance policy are usually tax-free9 under Section 10(10D) of the Income Tax Act, provided the premium does not exceed 10% of the sum assured and the policy meets specific eligibility conditions.
16.Is there a loan facility on all life insurance policies?
No, not all life insurance policies offer a loan facility.
17.Can a minor be appointed as a nominee in life insurance?
Yes, a child or a minor (below 18 years of age) can be appointed as a nominee for a life insurance policy. In case of a claim, an appointee chosen by the policyholder will file a claim on behalf of the minor nominee.
18.Is life insurance necessary for senior citizens?
Yes, senior citizens should have a life insurance policy so that during their retirement years, they can protect their families in a number of ways. For instance, a whole life insurance plan can offer extended coverage to all the family members till the insured reaches 100 years of age.
If they have a savings insurance plan or a retirement insurance plan, it can offer payout benefits as a regular income to the retired policyholder and their family, thus helping them sustain themselves financially and achieve their financial goals.
19.How do I find the best life insurance policy?
To find the best policy for life insurance, you should first ascertain the needs of your family members and how much financial support they will need in your absence. According to their requirements, you can choose a reputed life insurance provider that offers a policy and a flexible sum assured that covers these needs. If you buy a life insurance online, you can compare different plans on the official website of your insurance provider to select the best life insurance policy in India for your family and yourself.
20.Who Should Buy a Life Insurance Plan?
To buy life insurance policy, you generally need the following documents:
●Completed proposal form
●Age proof (PAN card, Aadhaar card, Birth certificate, etc.)
●Photo ID proof (PAN card, Aadhaar card, Passport, etc.)
●Address proof (Aadhaar card, Voter ID, Passport, etc.)
●Income proof (Bank statements, Salary slips, ITR receipts, etc.)
●Medical examination reports (if applicable)
●A recent passport-sized photograph
These requirements may vary slightly depending on the insurance provider.
1.Do life insurance policies offer only death benefits?
No, some life insurance policies offer death benefits as well as maturity benefits, payable to the policyholder on the maturity of the policy.
2.What types of deaths are covered by life insurance policies?
Tata AIA Life Insurance policies cover all types of deaths, including death by suicide. However, the terms and conditions for different types of deaths will vary.
3.Can I have multiple life insurance policies at once?
Yes, you may choose to have multiple life insurance policies at once. However, paying the premiums for so many policies can be very expensive, so it is advisable to have a comprehensive life insurance plan for yourself and your whole family, which can be much more cost-effective.
4.When can I add a rider to my life insurance plan?
You can add a rider23 to your life insurance plan at the time of the policy inception or during the policy anniversary while renewing the policy.
1.How to pay the life insurance online premium on a policy?
You can pay the life insurance premium online through any of the digital payment options available on the Tata AIA Life Insurance website after you purchase or renew your life insurance policy.
2.What are the premium payment modes when you buy a life insurance policy online?
When you buy life insurance policy, you can opt for single premium pay, limited pay, or regular pay for your life insurance policy, as per the offering of the plan. Do note that not all plans may offer all three premium payment modes.
3.How do I pay affordable premiums for my life insurance plan?
To be able to pay affordable premiums on your life insurance plan, ensure that you choose coverage that is neither too expensive nor inadequate. You can also calculate your life insurance premiums on a life insurance premium calculator and compare plans to opt for reasonable premiums.
4.What happens if I miss a premium payment?
Missing premium payments can lead to your life insurance policy lapsing, resulting in loss of coverage and accumulated cash value. Some policies offer a grace period to make late payments, but failure to pay within that period may result in policy termination.
5.Will my life insurance lapse if I stop paying the premiums?
If you do not pay your policy premiums within the grace period, the policy will lapse, and no benefits will be payable on the policy.
6.Do I have to continue paying the premiums if I surrender the policy?
Once you surrender your policy, your life insurance benefits will end immediately, terminating the coverage. Therefore, there will be no more premium payments. However, it is not advisable to surrender your policy so that you and your family can be protected throughout the policy term.
1.Can I file a claim during the policy term?
If you file a death claim, then this should take place if the policyholder dies during the policy term. In case of a maturity claim, you will get it once the policy matures.
2.What is a maturity claim in life insurance?
A maturity claim is a claim you get when your policy matures, and you are eligible to claim the benefits, which could be the guaranteed savings from the life insurance plan. These will be paid out to you in the form of a lump sum benefit or as a regular income, as per your choice.
3.Can you file multiple claims in a life insurance policy?
No, you can only file one death claim and one maturity claim (where applicable) on your life insurance policy. However, if you do have a health rider, you will be allowed to file claims for minor stage and major stage cardiac diseases and cancer, as mentioned in the rider document.
4.Will a life insurance death claim be payable if someone other than my nominee files the claim?
No, only the nominee mentioned on the policy document by you is eligible to file the death claim and receive the death benefits.
5.How to file a life insurance claim?
To file a claim, reach out to us through any of the following channels.
● Email us at: customercare@tataaia.com
● Call our helpline number - 1860-266-9966 (local charges apply)
● Walk into any of the Tata AIA Life Insurance Company branch offices.
● Write directly to us at:
● The Claims Department,
Tata AIA Life Insurance Company Limited
15th Floor, Centaurus,
Hiranandani Business Part,
Hiranandani Estate, Thane West,
Maharashtra, Pin code - 400607
IRDA Regn. No. 110
Disclaimers
The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.
Tata AIA Sampoorna Raksha Promise - Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN:110N176V13)
Tata AIA Maha Raksha Supreme Select - Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN: 110N171V16)
Tata AIA Shubh Flexi Income Plan (UIN: 110N207V03) - Individual, Non-Linked, participating, Life Insurance Savings Plan
The complete name of Tata AIA Fortune Guarantee Plus is Tata AIA Life Insurance Fortune Guarantee Plus (UIN: 110N158V14) - Individual, Non-Linked, Non-Participating, Life Insurance Savings Plan
The complete name of Tata AIA Fortune Guarantee Supreme - Individual, Non-Linked, Non-participating, Life Insurance Savings Plan (UIN:110N163V14)
Param Raksha Life Pro+ is designed for combination of benefits of following individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN:110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V02).
Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP, a non-participating, unit-linked, individual life insurance savings plan (UIN: 110L174V02), and Tata AIA Health Buddy, Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually.
These products are also available for sale individually without the combination offered/ suggested. This benefit illustration is the arithmetic combination and chronological listing of combined benefits of individual products. The customer is advised to refer the detailed sales brochure of respective individual products mentioned herein before concluding sale.
Tata AIA Smart Pension Secure (UIN: 110L182V09) - Non-Participating, Unit Linked, Individual Life Insurance Pension Plan
The complete name of Tata AIA Fortune Guarantee Pension Plan is Tata AIA Life Insurance Fortune Guarantee Pension Plan (UIN:110N1761V13) - A Non-Linked Non-Participating Individual Life Insurance Plan
1As per the duly approved product design and terms & conditions of the product, Illustrated premium of ₹501 is the monthly premium for a 20 yr. old female, Standard Life, Non-Smoker for ₹1 Cr. Sum Assured with Policy Term of 20 yrs. (Regular Pay) under Life Promise Option of Tata AIA Sampoorna Raksha Promise with first year premium discount of 10% for digital purchase and 8.5% for salaried person. Please refer Benefit Illustration for more details.
2This includes first year digital discount of 10% for Limited Pay/Regular Pay and 8.5% salaried discount. For Single Pay, 1% discount will be available for online purchase and salaried discount each.
3Under Life Promise Plus Option, an amount equal to the 100% of the Total Premiums Paid (excluding loading for modal premiums) shall be payable at the end of the Policy Term, provided the life assured survives till maturity and the policy is not terminated earlier
4Applicable to only non-early claims with more than 3 years of policy duration, non-investigation cases, up to Sum Assured of Rs. 50 lakhs. Applicable for branch walk in. Time limit to submit claim to Tata AIA Life Insurance is 2 pm on working days. Subject to submission of complete documents. Not applicable for ULIP policies and open title claims.
6Income Tax benefits would be available as per the prevailing income tax laws under old tax regime, subject to fulfilment of conditions stipulated therein. Income Tax laws are subject to change from time to time. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implications mentioned anywhere on this site. Please consult your own tax consultant to know the tax benefits available to you.
7All funds open for new business which have been completed 5 years since inception are rated 4 or 5 Star by Morningstar as of August 2025.
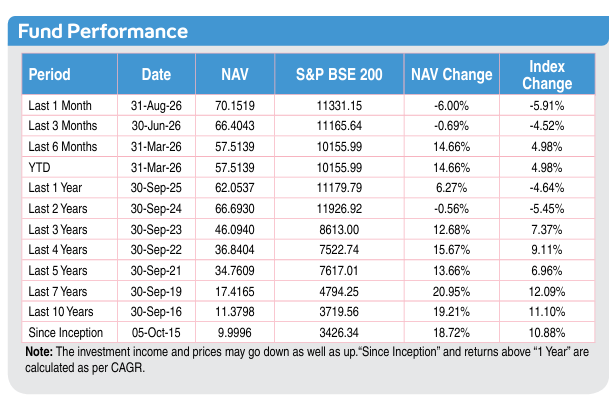
· 8Data from our TATA AIA fund factsheet shows the performance of TATA AIA Multi Cap fund & ULIF 060 15/07/14 MCF 110 as of July 2026. Benchmark of this fund is S&P BSE 200 – 100%.
9As per the duly approved product design and terms & conditions of the product, illustrated premium of ₹1 Lakh annually, Life cover ₹10 Lakh, Male age 35 Years, Non-Smoker, Policy Term: 37 Years, Gets return of premium at the end of Policy term ₹13.2 Lakh under Fortune Guarantee Supreme product plan. Please refer Benefit Illustration for more details.
10If Premium offset is opted, then the Survival Benefits during the PPT will be adjusted against the premium due to be paid. If the policy becomes Reduced Paid-Up before the first survival benefit payout (first income payout of premium offset), the Premium Offset feature will be discontinued, and future income and death benefit shall be paid as per terms and condition.
11Guaranteed returns in this plan depends on Age at Entry of life assured, Premium payment term, policy term, premium amount and plan option chosen.
12Return of Premium shall be the sum of Guaranteed Maturity Benefit plus Milestone Benefit and shall be payable at the end of the Income Period , irrespective of survival of the life insured(s) during the Income Period.
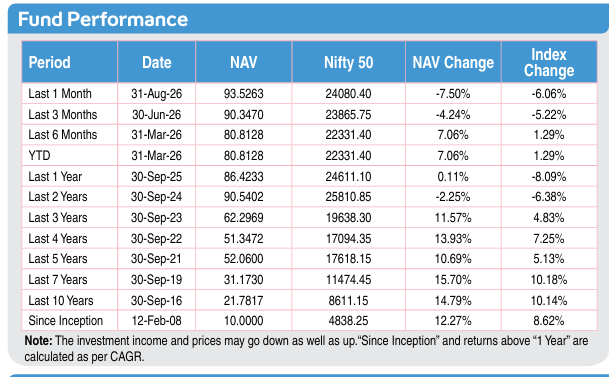
13Data from our TATA AIA fund factsheet shows the performance of TATA AIA Future Equity Pension fund & ULIF 020 04/02/08 FEP 110 as of July 2026. Benchmark of this fund is Nifty 50 -100%
14Partial withdrawals only available 3 times during the entire policy term and only for reasons specified in IRDA Regulations as amended from time to time
15Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.
16Riders are not mandatory and are available for a nominal extra cost. For more details on benefits, premiums and exclusions under the Rider, please contact Tata AIA Life's Insurance Advisor/Intermediary/ branch.
1798,01,699 families protected till 18th May 2026.
18Retail Sum Assured for FY’25-26 is Rs 9,00,876 Crores.
19As on 31st March 2026, the company has a total Assets Under Management (AUM) of ₹1,45,589 Crore.
20Illustrated Premium is the monthly premium excluding taxes for 20 yr. old female, Standard Life, Non-Smoker for 2 Cr. Sum Assured with Policy Term of 20 yrs. (Regular Pay) with Life Secure plan option salaried person. Please refer Benefit Illustration for more details. Tata AIA Life shall have the right to claim, deduct, adjust, recover the amount of any applicable tax or imposition, levied by any statutory or administrative body, from the benefits payable under the Policy. Kindly refer the sales illustration for the exact premium.
21“Guaranteed Annual Income” shall be a fixed percentage of the annualised Premium / Single Premium (excluding discount) payable in a year. Guaranteed Annual Income as per the chosen Income Frequency shall commence after maturity till the end of the Income Period, irrespective of survival of the life insured(s) during the Income Period.
22Cash bonuses (if declared) may be opted to be paid out at the end of the chosen pay-out frequency or as premiums offset. Alternatively, the cash bonus (if declared) can be chosen to be accumulated and paid out on maturity, death or surrender. Cash bonuses are applicable for Early income and Deferred income option. Please refer Brochure for additional details.
23©2025 Morningstar. All rights reserved. The Morningstar name is a registered trademark of Morningstar, Inc. in India and other jurisdictions. The information contained here: (1) includes the proprietary information of Morningstar, Inc. and its affiliates, including, without limitation, Morningstar India Private Limited (“Morningstar”); (2) may not be copied, redistributed or used, by any means, in whole or in part, without the prior, written consent of Morningstar; (3) is not warranted to be complete, accurate or timely; and (4) may be drawn from data published on various dates and procured from various sources and (5) shall not be construed as an offer to buy or sell any security or other investment vehicle. Neither Morningstar, Inc. nor any of its affiliates (including, without limitation, Morningstar) nor any of their officers, directors, employees, associates or agents shall be responsible or liable for any trading decisions, damages or other losses resulting directly or indirectly from the information.
24ULIP policies issued on or after 1st February 2021 if the amount of aggregate annual premium payable in the financial year for all such policies does not exceeds INR 2,50,000/-. Subject to fulfillment of conditions mentioned in 10(10D).
25The word Guaranteed and Guarantee means the annuity payout is fixed at inception of the policy and will be payable for whole of life or till death of the Annuitant(s).
26Return of Purchase price means return of all premiums paid excluding any extra premium, any rider premium, taxes and other statutory levies, if applicable
27Premium excluding taxes for age group of 18 to 50, Male, Standard life, Plan Option 1 (Regular Income), Policy term 15 years, Income term 30 years. Total Guaranteed Benefit: Rs. 47,49,400. Please refer Benefit Illustration for more details.
Premium is subject to applicable taxes, cesses & levies which will be entirely borne/paid by the Policyholder, in addition to the payment of such Premium. Tata AIA Life shall have the right to claim, deduct, adjust, recover the amount of any applicable tax or imposition, levied by any statutory or administrative body, from the benefits payable under the Policy. Kindly refer the sales illustration for the exact premium.
28Only available with cash bonus option. The current loyalty addition rate on the Sub-wallet will be 6.00% compounding monthly. The loyalty addition rate shall be at which RBI absorbs liquidity which currently is the Standing Deposit Facility (SDF) rate. The current Standing Deposit Facility rate is 6.00% p.a. and the same shall be reviewed bi-monthly. The Company may in future change the reference rate from Standing Deposit Facility rate to some other index.
Some benefits are guaranteed, and some benefits are variable with returns based on the future performance of your insurer carrying on life insurance business. If your policy offers guaranteed benefits, then these will be clearly marked “guaranteed’ in the illustration table on this page. If your policy offers variable benefits, then the illustrations on these pages will show two different rates of assumed future investment returns. Currently these are assumed rate of returns as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.
Tata AIA Life Insurance Company Limited is only the name of the Insurance Company &, Tata AIA Smart Pension Secure, Tata AIA Smart Sampoorna Raksha Supreme, Tata AIA Smart SIP is only the name of the Unit Linked Life Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns.
Linked Life Insurance products are different from traditional insurance products and are subject to risk factors.
Various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns. The premium paid in Linked Life Insurance policies is subject to investment risks associated with capital markets and publicly available index. The NAV of the units may go up or down based on the performance of Fund and factors influencing the capital market/publicly available index and the insured is responsible for his/her decisions. On survival to the end of the policy term, the Total Fund Value including Top-Up Premium Fund Value valued at applicable NAV on the date of Maturity will be paid
Investments are subject to market risks. The Company does not guarantee any assured returns. The investment income and price may go down as well as up depending on several factors influencing the market
Please know the associated risks and the applicable charges, from your insurance agent or the Intermediary or policy document issued by the insurance company. Please make your own independent decision after consulting your financial or another professional advisor
Past performance is not indicative of future performance. Returns are calculated on an absolute basis for a period of less than (or equal to) a year, with reinvestment of dividends (if any)
If your policy offers variable benefits, then the illustrations on this page will show two different rates of assumed future investment returns. Currently the gross investment returns are stipulated as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.
Life insurance cover is available under the solution. For more details on risk factors, terms and conditions please read Sales Brochure carefully before concluding a sale.
Risk cover commences along with policy commencement for all lives, including minor lives. Buying a Life Insurance Policy is a long-term commitment. An early termination of the Policy usually involves high costs, and the Surrender Value payable may be less than the all the Premiums Paid. In case of non-standard lives and on submission of non-standard age proof, extra premiums will be charged as per our underwriting guidelines. All Premiums and interest payable under the policy are exclusive of applicable taxes, duties, surcharge, cesses, or levies which will be entirely borne/ paid by the Policyholder, in addition to the payment of such Premium or interest. Tata AIA Life shall have the right to claim, deduct, adjust, and recover the amount of any applicable tax or imposition, levied by any statutory or administrative body, from the benefits payable under the Policy.
L&C/Advt/2026/Jun/3530
Last updated on 23 Oct 2026
New user? Our experts are happy to help.
Thank you for sharing your details.
Our representative will contact you soon.





 Get ₹ 1 Cr Life Cover at ₹ 502/month1


 10 mins read