Benefits of Term Insurance

A term insurance plan provides financial protection to your family in case of your untimely demise. It offers a high life cover at an affordable premium,... Read more making it a practical option for long-term financial planning. You can also customise your policy by adding optional riders8 based on your protection needs. This article covers the key term insurance benefits.Read less

Almost there!

Your premium calculation is in progress

Verify OTP

Kindly enter the OTP sent to

+91 736365432

Please enter valid OTP

01:60

Didn't receive OTP?

Technical issue detected - please continue without OTP verification
Success Icon

Success

Your details have been successfully submitted. A representative from Tata AIA Life Insurance will call you soon.

Failure Icon

Failure

Your details could not be saved.
Please try again.

Refresh

Term Insurance Calculator

Here's your customized plan

Buy now Next arrow

Get Life Cover of ₹1 Crore by paying a premium of

₹7,085/month

Total premium: ₹14.09 Lakh

tooltip
  • 1st year premium (with discount): 
₹21,749/month
  • 2nd year onwards premium: ₹8,287/month
close

savingSave ₹1,202 with discounts

₹ 4.2 Lakh
₹ 1 Crore
You Pay (Total)
You Get (Life Cover)

Discounts

10% Online discount
tooltip
close

10% discount on 1st year premium is applicable on online purchase. This discount is auto-applied and can’t be removed

8.5% Salaried discount
tooltip
close

8.5% discount on 1st year premium is applicable for salaried personnel. You will need to share your corporate email ID if you opt for this discount. This discount is auto-applied if you select ‘Salaried’ as your occupation and can’t be removed

25%Tata Group Employee Discount
tooltip
close

Applicable only if the policy is bought digitally. Some discounts will not be available when this option is selected.

1% Autopay discount
tooltip
close

1% discount on 1st year premium for all payments paid through any permissible electronic mode debited through an auto-debit mandate. Maximum discount capping: ₹100 over the year.

2% Milestone discount
tooltip
close

2% discount on 1st year premium on these milestones

Event Eligibility
Wedding (1 wedding only) Within 6 months before or after the date of wedding
Birth/ Adoption of 1st child* Within 6 months before or after the birth/ adoption date
Home loan Within 6 months of loan getting sanctioned
First job Within 6 months of joining date

*Policy issuance eligibility for female customers will be determined by Board Approved Underwriting Policy (BAUP)

The above milestones cannot be clubbed to avail more discount, Such discount shall be capped to a maximum of ₹500 over the year.

15% lower premium for women (every year)

Tata AIA Sampoorna Raksha Promise - Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN: 110N176V12)

Term Insurance Calculator

Unable to load your customized plan

Please try again after some time

Our sales representative will connect with you soon to assist further

Try again

Term Insurance Calculator

Request timeout

We're facing a technical issue. Please try again after some time

Our sales representative will connect with you soon to assist further

Try again
Term Insurance Benefits Banner Image

120 year old female (Standard Life, Non-Smoker), regular pay, 20 year policy term

Term Insurance Calculator

Are you an NRI?

Icon

No

Yes
No

Gender

Male

Male
Female

Do you smoke?

Icon

No

Yes
No

Ellipse
Ellipse
Ellipse
Ellipse
Vishal-Kapoor

Written by

Vishal Kapoor

Desktop-Vishal
Insurance Expert

Vishal Kapoor

Vishal Kapoor, AVP - Brand & Product Marketing at Tata AIA, has over 17 years of experience in the BFSI sector. He is responsible for driving brand strategy, product & channel marketing campaigns.

Girish-J-Kalra

Reviewed by

Girish J Kalra

Desktop-Girish
Chief Marketing Officer

Girish J Kalra

Girish J Kalra, Chief Marketing Officer at Tata AIA, leading the organizations marketing & corporate communication initiatives..

What are the key benefits of term insurance plans?

Term insurance provides financial protection to your family if you pass away during the policy term. The nominee receives the applicable death benefit, which can help cover household expenses, outstanding loans and future financial commitments. Understanding the term insurance benefits can help you assess how this type of life cover fits into your financial planning. Depending on the policy, you may also have options for different payout structures and additional riders8 to extend protection. These features make term insurance a useful way to prepare for financial responsibilities that your family may need to manage in your absence.
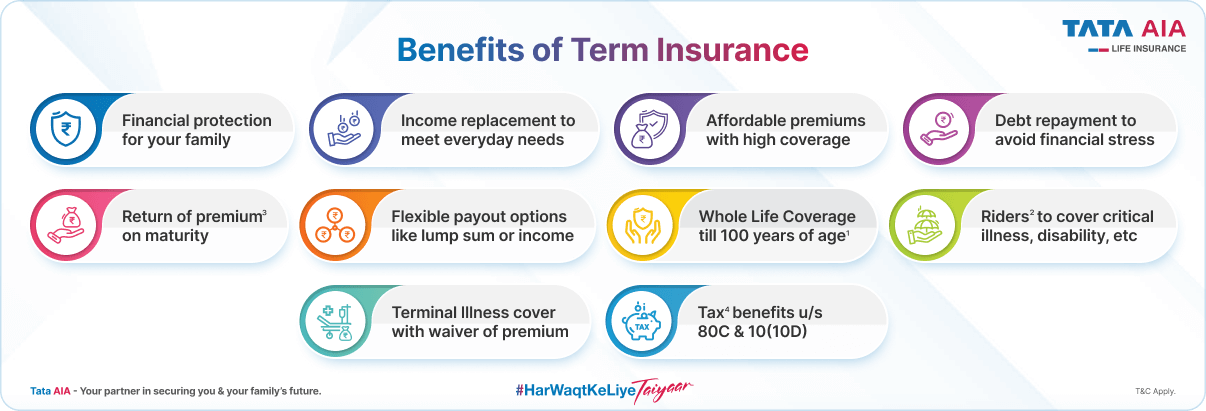
Helps secure your family's financial future

One of the key benefits of term life insurance is that it provides financial support to your nominee in case of your untimely demise, helping them manage future financial responsibilities.

Affordable premiums

Term insurance can provide a substantial amount of life cover for a comparatively affordable premium, particularly when compared with life insurance products that also include savings or investment components. Since a basic term plan primarily provides life protection, the premium is generally focused on providing the required cover.

Offers life cover at affordable premiums

Term insurance provides a high sum assured at relatively affordable premiums. The premium depends on factors such as age, policy term, health, and the chosen coverage amount.

Provides income replacement for dependants

The claim amount can help replace the policyholder's income, allowing family members to manage regular expenses, outstanding liabilities, and future financial commitments more comfortably.

Gives flexibility in death benefit payouts

Many term insurance plans allow you to choose how the claim amount is paid to your nominee. You may opt for a lump sum payout, regular monthly income, or a combination, depending on your family's financial needs.

Allows you to customise coverage with riders

You can enhance your policy by adding optional riders8 such as accidental death, critical illness, or waiver of premium. These add-ons provide broader financial protection by covering specific risks beyond the base policy.

Offers coverage against critical illnesses

With an optional critical illness rider8, you can increase the financial support available to your nominee if death occurs due to a covered accident. It offers an additional payout over and above the base sum assured, as per policy conditions.

Provides accidental death protection

An accidental death benefit rider8 can increase the financial support available to your nominee if death occurs due to a covered accident. It offers an additional payout over and above the base sum assured, as per policy conditions.

Includes tax advantages

Eligible premiums paid towards a term insurance plan may qualify for tax deductions5 under the applicable provisions of the Income Tax Act. In addition, the death benefit received by the nominee is generally tax-exempt5, subject to prevailing tax laws.

Offers different plan options

Term insurance is available in different variants, including level term, increasing term, decreasing term, return of premium, and convertible plans. This allows individuals to choose coverage based on their financial goals and protection requirements.

Best Tata AIA Term plans

How term insurance works?

A term insurance policy is a life insurance agreement that provides coverage for a specified period in exchange for regular premium payments. The policyholder selects the sum assured, policy term and premium payment frequency when applying for the plan. The insurer assesses the application based on details such as age, medical history, occupation and lifestyle before deciding whether to issue the policy.
 

Once the policy is issued, the life cover remains active as long as the policyholder meets the applicable terms and premium payment requirements. If the insured person passes away during the policy term, the nominee can submit a claim. After the insurer assesses and approves the claim, the applicable death benefit is paid according to the policy conditions.
 

If the policyholder survives the term, a standard term insurance plan generally ends without a maturity payout. A plan with a return of premium feature may provide a refund of eligible premiums if the stated conditions are met. The available benefits, exclusions and payout options vary by policy, so these details are important when comparing plans.

Types of term insurance plans

Term insurance plans come in different forms to accommodate varying financial responsibilities and coverage preferences. Understanding the main types can help you compare the available options.

  • Level term insurance plan

    The sum assured remains unchanged throughout the policy term. This option may suit people who want a consistent level of financial protection for their dependants.

  • Increasing term insurance plan

    The sum assured increases over a specified period, depending on the policy terms. This structure may help account for rising household expenses and changing financial responsibilities over time.

  • Decreasing term insurance plan

    The sum assured gradually reduces during the policy term. It may be suitable for people whose financial liabilities, such as a repayment-based loan, are expected to decline over time..

  • Term insurance with return of premium

    This plan includes a feature under which eligible base premiums may be returned if the policyholder survives until the end of the policy term and meets the specified conditions. Premiums may be higher than those of a comparable standard term plan, and the refund may exclude rider8 premiums, taxes5 or other charges, as specified in the policy..

  • Convertible term insurance plan

    A convertible plan allows the policyholder to convert the term cover into another eligible type of life insurance, subject to the insurer's rules and the policy conditions. The conversion options, deadlines and additional costs can differ between policies..

Benefits of purchasing a term insurance plan early in life

Purchasing term insurance early can help you arrange financial protection before your responsibilities grow. One of the key term life insurance benefits is the possibility of securing a substantial life cover at a comparatively lower premium when you are younger and meet the insurer's underwriting requirements. Early planning can also help you obtain coverage while you have fewer health-related complications, although acceptance and pricing depend on individual circumstances. Reviewing the benefits of term insurance at an early stage can help you understand how coverage may support your family over the years.

Lower premiums

Purchasing a term life insurance early helps you lock in a lower premium. Since age and health influence premium calculations, buying a policy in your 20s or early 30s may help reduce the amount payable throughout the policy term.

Longer Coverage

Starting early also increases the likelihood of choosing a longer policy tenure. For example, someone purchasing a plan at 25 may be able to stay covered until 85 or 90 years of age, while a person buying later may have a comparatively shorter coverage period.

Higher Sum Assured 

Buying early may also improve your eligibility for a higher sum assured. Younger applicants with fewer health concerns are often considered lower-risk, allowing them to secure a larger life cover based on the insurer's underwriting guidelines and financial eligibility.
Previous Icon
nextarrow Next Icon

How can term insurance safeguard your family’s future?

Term insurance can help your family manage financial responsibilities if your income is no longer available. The death benefit can provide funds for immediate expenses and longer-term needs, subject to the policy's terms and claim approval.

  1. Replacing lost income: The payout can help dependants manage everyday expenses such as groceries, rent, utility bills and school fees. This financial support may help the family maintain its standard of living while adjusting to a loss.
  2. Managing outstanding debts: Home loans, personal loans and other liabilities can place pressure on family finances. The death benefit may be used to repay outstanding balances, reducing the risk that dependants need to sell assets or take on additional borrowing.
  3. Supporting children's education and future goals: Education costs and other long-term commitments can require substantial funding. The payout can help the family continue planning for these expenses even when the policyholder's income is no longer available.
  4. Maintaining financial stability: A sudden loss can affect both emotional wellbeing and household finances. The policy payout can provide a financial reserve for essential needs while dependants reassess their income and expenses.
  5. Providing flexibility through payout options: Depending on the policy, the nominee may receive the death benefit as a lump sum, instalments or a combination of both. Reviewing the available options can help you understand how the payout may support your family's financial needs.

Key riders to enhance term benefits

Term insurance riders8 are optional additions that can extend the coverage of a basic policy. They generally involve an additional premium and apply only under the conditions specified in the policy. Comparing available term insurance riders8 can help you understand whether extra protection is relevant to your circumstances.

frame1

Critical illness rider

This rider8 may provide a lump-sum payout if the insured person is diagnosed with a critical illness listed in the policy and meets the applicable conditions. The amount may help cover treatment costs, household expenses or other financial commitments during recovery. Check the covered illnesses, survival period, exclusions and claim requirements before selecting this option.

frame2

Accidental death benefit rider

An accidental death benefit rider8 may provide an additional payout if the insured person dies due to an accident covered by the policy. This benefit is paid in addition to the base cover when the policy's requirements are met. The definition of a covered accident and any exclusions should be reviewed carefully.

frame3

Waiver of premium rider

This rider8 may waive future premiums if the insured person experiences a qualifying disability or diagnosis specified in the policy. It can help keep the base policy active without requiring the policyholder to continue making eligible premium payments during the covered circumstances.

frame4

Income benefit rider

An income benefit rider8 may provide regular payments to the nominee in addition to, or as part of, the death benefit structure, depending on the policy. This arrangement can help dependants meet recurring expenses instead of relying entirely on a single payout.

The availability and terms of these riders8 vary between insurers. Consider the additional premium, coverage limits, exclusions and claim conditions before deciding which options fit your needs.

How to choose the best term Insurance with the right sum assured?

You should purchase a term insurance policy that has all the features and benefits you need, along with a lower premium. Ideally, your coverage should equal or exceed 10–15 times your annual income. As an example, if your income is around Rs 15 lakh per year, a suitable life insurance policy would range between Rs 1.5 crore and Rs 2.25 crore. For enhanced protection, individuals with higher financial responsibilities or goals may also consider a Rs 5 crore term insurance plan.

Why should you purchase a term insurance plan?

Unforeseen life events can lead to financial instability for your family in your absence. In such a case, a term insurance plan benefits by offering long-term financial security. Here are some key reasons to consider buying one:

Familys-needs.png

Financial protection against uncertainties

One of the primary reasons to buy a term insurance India policy is to protect your family's finances against unforeseen events. In case of the policyholder's untimely demise or, where applicable, disability covered under the policy or rider8, the financial payout may help your loved ones manage household expenses, future goals, and outstanding liabilities.

Whole-Life-Cover.png

Coverage for critical illnesses

Many term insurance plans allow you to enhance your policy with a critical illness rider8. If you are diagnosed with a covered critical illness during the policy term, the rider may provide a lump sum benefit that can help manage treatment costs without significantly affecting your savings.

Pay-your-Way.png

Option to enhance protection with riders

Apart from life cover, you can customise your policy by adding optional riders8 such as accidental death benefit, accidental total and permanent disability, waiver of premium, or critical illness cover. These riders provide additional protection based on your financial responsibilities and changing life needs.

OPD-Care-cover.png

Tax benefits under applicable provisions

A term insurance plan also offers tax advantages, subject to prevailing tax laws. Eligible premiums may qualify for deductions5 under the applicable provisions of the Income Tax Act, while premiums paid towards eligible health riders8 may also qualify for additional tax5 benefits. Further, the death benefit payable to the nominee is generally tax-exempt5, subject to applicable conditions.

Steady-Flow-of-Income.png

Flexible premium payment options

Most insurers offer flexible premium payment frequencies, including monthly, quarterly, half-yearly, annual, or single premium options. This flexibility allows you to choose a payment schedule that aligns with your income and financial commitments while keeping the policy active throughout the selected term.

How to choose the best term insurance policy?

Selecting the right term life  insurance policy involves evaluating your financial responsibilities, future goals, and coverage requirements. Let’s understand how to choose the best term insurance policy:

Assess your life cover requirement

Choose a sum assured that can adequately support your family's financial needs in your absence. As a general guideline, the life cover may be around 10–15 times your annual income. For example, if you earn ₹15 lakh annually, a cover of ₹1.5 crore to ₹2.25 crore may be suitable, depending on your financial obligations.

Compare policy features and benefits

Look beyond the premium and compare the policy's features, available riders8, claim settlement process, payout options, and flexibility. Choosing a plan that aligns with your long-term financial needs can provide more comprehensive protection.

Balance premium affordability with adequate coverage

While an affordable premium is important, it should not come at the cost of insufficient coverage. If you have higher liabilities, multiple dependants, or long-term financial goals, you may consider opting for a higher sum assured, such as ₹5 crore, provided it suits your financial situation.

Looking to buy a new insurance plan? 

Our experts are happy to help you!

Our experts are happy to help you!

Are you an NRI?

Yes
No

+91

Conclusion

Term insurance can provide financial support to your family if you pass away during the policy term. The death benefit may help replace lost income, repay liabilities and fund important future expenses. Understanding the term insurance plan advantages, available policy types and optional riders8 can help you compare coverage options more effectively. You may also review the term plan tax5 benefits applicable to your circumstances under current tax laws, as eligibility depends on the policy and relevant conditions. Choosing a suitable plan involves assessing your family's financial needs, the required sum assured, the policy term and the affordability of premiums.

1.What is the primary advantage of term insurance?
The primary advantage of term insurance is its ability to provide extensive life cover at an economical premium. It ensures financial security for dependents in the event of the policyholder's unexpected demise.

2.What is the right age to purchase a term plan?
You should purchase a term plan as early as you become eligible and start working. Purchasing a term plan early in life ensures lower premiums and allows for a longer coverage duration.

3.What is the right amount for term insurance?
The suitable term insurance amount depends on your income, financial responsibilities, and long-term goals. It should be sufficient to cover your family’s living expenses, debts, and future needs.

4.How should I decide on the required term insurance coverage?
To determine the term insurance coverage, you should consider the following factors:

● Your family’s future financial requirements
● Long-term financial goals and ongoing commitments
● Potential emergency expenses
● Outstanding loans and liabilities

5.What is the difference between the benefits of term insurance and life insurance?
Life insurance offers both death benefit and maturity benefits to the beneficiary, whereas term insurance provides the benefit of life cover. For more details, read here.

6.Can I purchase multiple term insurance plans?
You can buy multiple term plans if needed. However, opting for a single plan with higher coverage offers convenience, simplified premium management, and comprehensive protection for your family’s financial future.

7.What are the optional term plan benefits?
Riders8 are optional add-ons to a term insurance plan that offer enhanced protection against specific risks like critical illness, disability, or accidental death, for an additional but affordable premium.

8.Can I extend my term insurance to ensure critical illness coverage?
Yes, some term insurance plans offer critical illness coverage through a rider8, which provides an additional sum if the policyholder is diagnosed with a listed illness, enhancing financial protection beyond the base policy.

9.What are the benefits of using term insurance to cover outstanding debts?
Term insurance helps repay outstanding debts in case of the policyholder’s demise, ensuring the family is not burdened financially and can retain assets without the need for loans or sale of assets.

10.What are the tax benefits in term insurance?
The premiums paid for a term plan qualify for tax5 deductions under Section 80C, while the death benefit received by nominees is fully exempt from tax5 under Section 10(10D) of the Income Tax Act.

11.Are death benefits from Term Insurance taxable?
No, death benefits received from a term insurance policy are not taxable5. They are exempt under Section 10(10D) of the Income Tax Act, subject to the fulfilment of specified conditions.

12.What are the benefits of purchasing term insurance online?
Buying a term plan online saves time and effort. You can compare options, add suitable riders8, and make premium payments instantly through secure digital channels, all from the comfort of your home.

13.What happens if the policyholder survives the policy period?
A pure term plan offers no payout if the policyholder survives the term. However, a return of premium plan provides a maturity benefit and provides refunds of the total premiums paid during the policy term.

14.Does a term insurance plan give maturity benefits?
If you choose a return of premium term plan and survive the policy term, you will receive a maturity benefit equal to the total premiums paid, excluding applicable taxes.

15.Can I withdraw funds from my term insurance plan?
Term insurance does not permit fund withdrawals during the policy term. However, in the event of the policyholder’s death, the sum assured is paid to beneficiaries as a lump sum or regular income.


  • Tata AIA Sampoorna Raksha Promise - Non-Linked, Non-Participating, pure risk, Individual Life Insurance Product (UIN:110N176V13)

  • Tata AIA Maha Raksha Supreme Select - Non-Linked, Non-Participating, Pure Risk, Individual Life Insurance Product (UIN: 110N171V16)

  • 1Illustrated premium of ₹678 is the monthly premium excluding taxes for a 20 yr. old female, Standard Life, Non-Smoker for ₹1.5 Cr. Sum Assured with Policy Term of 20 yrs. (Regular Pay) under Life Promise Option of Tata AIA Sampoorna Raksha Promise with first year premium discount of 10% for digital purchase and 8.5% for salaried person. Please refer Benefit Illustration for more details.

  • 2Under Life Promise Plus Option, an amount equal to the 100% of the Total Premiums Paid (excluding loading for modal premiums) shall be payable at the end of the Policy Term, provided the life assured survives till maturity and the policy is not terminated earlier.

  • 3Applicable to only non-early claims with more than 3 years of policy duration, non-investigation cases, up to Sum Assured of ₹50 Lakh. Applicable for branch walk in. Time limit to submit claim to Tata AIA Life Insurance is 2 pm on working days. Subject to submission of complete documents. Not applicable for ULIP policies and open title claims.

  • 4Not applicable under PoS, please refer sales brochure for more information

  • 5Income Tax benefits would be available as per the prevailing provisions of income tax laws, subject to fulfillment of conditions stipulated therein. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implications mentioned anywhere on this site. Please consult your own tax consultant to know the tax benefits available to you. 

  • No Goods and Service Tax shall be applicable on Individual life insurance products as per prevailing laws.

  • 6This includes first year digital discount of 10% for Limited Pay/Regular Pay and 8.5% salaried discount. For Single Pay, 1% discount will be available for online purchase and salaried discount each.

  • 7Illustrated premium of ₹804 is the monthly premium excluding taxes for a 20 yr. old female, Standard Life, Non-Smoker for ₹2.0 Cr. Sum Assured with Policy Term of 20 yrs. (Regular Pay) under Life Promise Option of Tata AIA Sampoorna Raksha Promise with first year premium discount of 10% for digital purchase and 8.5% for salaried person. Please refer Benefit Illustration for more details.

  • 8Rider is not mandatory and is available for a nominal extra cost. For more details on benefits, premiums, and exclusions under the Rider, please contact Tata AIA Life's Insurance Advisor/ branch.

  • This product is underwritten by Tata AIA Life Insurance Company Ltd.

  • The plan is not a guaranteed issuance plan, and it will be subject to company’s underwriting and acceptance.

  • Insurance cover is available under this product.

  • For more details on risk factors, terms and conditions please read sales brochure carefully before concluding a sale. The precise terms and condition of this plan are specified in the Policy Contract.

  • Buying a Life Insurance Policy is a long-term commitment. An early termination of the Policy usually involves high costs, and the Surrender Value payable may be less than the all the Premiums Paid.

  • In case of non-standard lives and on submission of non-standard age proof, extra premiums will be charged as per our underwriting guidelines. 

  • L&C/Advt/2026/Oct/5699