







Call us
Call us
 FOR EXISTING POLICY
Have query on premium, payout or any servicing need?
Call us:
 FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY (NRIs)
Note: Consent is provided to Tata AIA Life Insurance Company Limited to contact you by calling/giving missed call to the above numbers.
Thank you for sharing your details. To receive a call from Tata AIA Financial Advisor.
reCAPTCHA is not working.
No relevant search results found.
Popular searches
Continue from where you left of
A 1 crore health insurance plan is a medical cover to pay for healthcare expenses up to 1 cr. As healthcare costs rise, the extensive coverage... Read more ensures financial protection during medical emergencies. A suitable plan provides access to the latest medical technology and good healthcare facilities. It acts as a safety net for you and your family. Read less
A 1 crore health insurance is an insurance plan with a ₹1 crore cover to pay for medical expenses. This insurance plan helps cover medical treatments like organ transplant and robotic surgery. This means that you are covered for expensive healthcare services as well. The plan helps ease the burden and cover your medical bills.
A 1 cr health insurance plan works like other policies, but it has a larger limit. The insurer offers a ₹1 crore coverage with payment of the yearly fee. In the case of a medical claim, the insurance company pays your hospital bills up to the full plan amount. They can pay the hospital directly or refund you the money later.
A "restoration" or "refill" benefit, which instantly restores the ₹1 crore limit if it is spent by one claim. This is another characteristic of most 1 cr health insurance plans. This feature offers protection for later, unrelated diseases within the same policy year.
A Non-Participating, Unit-linked, Individual Health Insurance Plan (UIN: 110L180V01)
Non-Participating, Non-Linked Individual Health Product (UIN: 110N186V01)
₹1 Crore health insurance coverage means that after 10 years, you’ll still be able to finance healthcare care without risking your financial well-being.
A ₹1 crore health cover provides a high sum insured, but the coverage offered under the policy is equally important. Factors such as exclusions, waiting periods, deductibles and room-rent limits may affect the benefits available. The policy should also match the healthcare needs of the people covered. Consider the following factors before choosing a ₹1 crore health insurance policy:
Age, medical history and family size are some factors to consider when choosing health insurance. A family floater covers several family members under one shared sum insured, while an individual policy provides separate coverage for each person.
Consider the treatment and expenses covered by the plan. This may include hospitalisation, daycare procedures, pre- and post-hospitalisation expenses, and ambulance services. Exclusions and waiting periods are also essential to consider while selecting the policy.
A deductible refers to an amount which is paid by the policyholder before the sum insured becomes applicable. A co-payment means that the policyholder pays a specific percentage of an admissible claim. Both deductible and co-payment impact on the amount the policyholder pays while making a claim.
A ₹1 crore sum insured does not mean that every expense is covered up to ₹1 crore. A policy may have sub-limits for certain treatments or room-rent restrictions. The Customer Information Sheet provides key details about exclusions, sub-limits, deductibles and waiting periods.
Cashless treatment is available at network hospitals, subject to the policy conditions. Checking the insurer's hospital network helps identify whether commonly used hospitals are included.
The 1 crore health insurance premium may differ across policies. Premium should not be the only point of comparison. The coverage, exclusions, deductibles, co-payments, sub-limits and other benefits should also be considered.
For the 1 crore health insurance plan, applicants must have a certain age and health requirements.
The total cost of your health insurance coverage is affected by several factors.
A ₹1 crore health insurance policy provides a higher sum insured for eligible healthcare expenses. Some of its key benefits include:
Medical treatment, surgery and hospitalisation may involve substantial expenses. A ₹1 crore sum insured provides a higher coverage limit for eligible costs covered under the policy.
A family floater allows multiple family members to use the same sum insured. This provides a shared pool of coverage for eligible medical expenses, subject to the policy terms.
Health insurance may cover hospitalisation and certain daycare procedures. Depending on the policy, pre- and post-hospitalisation expenses and ambulance charges may also be included.
Cashless treatment allows eligible medical expenses to be settled directly with a network hospital, subject to approval and the policy conditions. This reduces the need to arrange the entire eligible treatment cost upfront.
Some policies offer additional benefits for areas such as maternity or outpatient treatment. These benefits may come with separate conditions or an additional premium.
Premiums paid towards eligible health insurance policies may qualify for a deduction4 under Section 80D, subject to applicable tax provisions. The deduction available may depend on factors such as the age of the insured person and parents.
One crore health insurance can be the top priority for city residents and single individuals.
A ₹1 crore medical insurance plan can generally be purchased online through a few basic steps. The process may vary between insurers.
Start by considering the age, health profile and family members who need coverage. Existing health insurance and expected healthcare expenses may also be taken into account.
Compare 1 crore medical insurance plans based on their coverage and policy conditions. Waiting periods, exclusions, deductibles, co-payments, sub-limits and network hospitals are some factors to consider.
An online premium calculator can be used to check the applicable premium. The 1 crore health insurance premium per month may vary based on age, health profile, family size and selected benefits.
The proposal form requires details such as personal information, contact details and medical history. Health-related information should be provided accurately.
Some applicants may need to undergo medical tests or provide medical records before the policy is issued. The requirement depends on the insurer and the applicant's profile.
After checking the premium and policy details, the premium can be paid through the payment options provided by the insurer.
Once the policy is issued, check the sum insured, insured members, coverage, exclusions and other conditions. The policy documents should be kept safely for future reference.
To start a ₹1 Crore health insurance policy, standard KYC and medical data are required.
The patient's urgent medical care is given priority in the well-planned claim process.
The cost of a ₹1 crore health insurance policy depends on factors such as age, health profile, family size and selected benefits. The following points may help in managing the premium:
Two policies may have different premiums even when they offer the same sum insured. Compare the coverage, exclusions, deductibles, co-payments and sub-limits along with the premium.
Age is a primary factor in calculating health insurance premiums. Purchasing a policy at a younger age may help keep the premium relatively manageable. The actual cost of your health insurance is, however, dependent on the company and policy you choose.
An individual policy and a family floater work differently. A combination of a base policy and top-up cover may also be considered depending on the coverage required.
Add-ons provide additional coverage but may increase the premium. Consider the benefits offered by each add-on before adding it to the policy.
A higher deductible may reduce the premium. However, it also means that the policyholder needs to pay a larger portion of eligible expenses before the insurer's coverage begins.
A co-payment reduces the portion of the claim paid by the insurer. The premium and the policyholder's share of expenses should therefore be considered together.
Some policies provide cumulative bonuses or other benefits for claim-free periods. The policy wording explains how these benefits affect the available sum insured.
Healthcare needs may change with age and changes in family circumstances. Reviewing the policy at renewal helps determine whether the existing coverage continues to meet those needs.
The premium does not represent the entire cost of a health insurance policy. Deductibles, co-payments and sub-limits may also affect the amount paid during a claim. These costs should be considered when comparing the 1 crore health insurance premium.
A ₹1 crore health cover may provide a higher sum insured. However, it is essential to look at the inclusions offered. The premium, exclusions, waiting periods, deductibles, co-payments and other terms and conditions will have an impact on how the policy works. Comparing these features will help you understand the coverage that will be provided under a policy before buying.
The total cost of health insurance is determined by several factors:
The first step toward complete financial safety is to get the best 1 crore health insurance policy. A good policy suggests that your life savings are unaffected in an emergency in a time of high medical bills and unexpected emergencies. You can take advantage of reduced premiums and complete long-term protection by making a 1 cr health insurance policy a plan early in life.
1.
Premiums can be between 8000 to 12000 annually for young people.
2.
Yes, premiums are deductible under Section 80D of the Income Tax4 Act.
3.
Based on your age, you can get an estimate from an online premium calculator.
4.
Both benefit from it, particularly as an affordable family floater.
5.
Many insurance policies offer lifetime flexibility; the average entrance age is 65.
The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.
Tata AIA Pro-Fit comprises of Tata AIA Health Pro, A Non-Participating, Unit-linked, Individual Health Insurance Plan (UIN: 110L180V02), Tata AIA Health Secure, A Non- Participating, Unit Linked, Individual Health rider (UIN: 110A050V01) & Tata AIA Health Buddy Non-Participating, Non-Linked Individual Health Product (UIN: 110N183V02) Tata AIA Smart Health Pro and Tata AIA Health Buddy are also available for sale individually.
Tata AIA Health SIP (UIN:110L184V01) - Non-participating, Unit Linked, Individual Health Insurance Plan
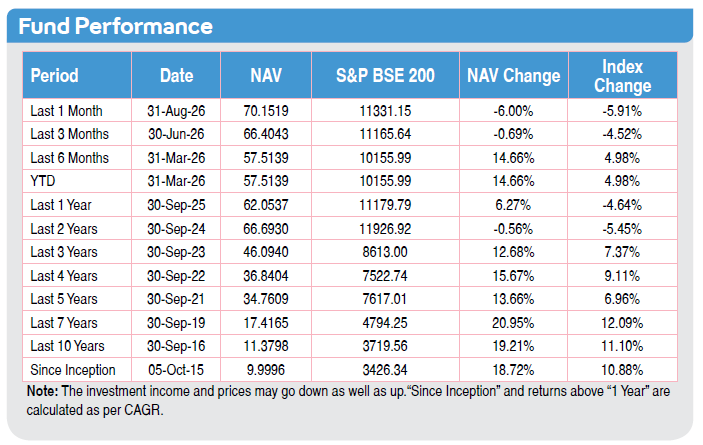
1Data from our Tata AIA fund fact sheet shows the performance of Tata AIA Multi Cap fund & SFIN NO: ULIF 060 15/07/14 MCF110 as on September 2026. Benchmarked with Nifty 50.
2Get daily cash benefit of up to ₹20,000 on hospitalization & Up to ₹40,000 on ICU admission
3Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.
4Income Tax benefits would be available as per the prevailing income tax laws, subject to fulfillment of conditions stipulated therein. Income Tax laws are subject to change from time to time. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implication mentioned anywhere in this document. Please consult your own tax consultant to know the tax benefits available to you.
No Goods and Service Tax shall be applicable on Individual life insurance products as per prevailing laws
5Riders are not mandatory and are available for a nominal extra cost. For more details on benefits, premiums, and exclusions under the Rider, please contact Tata AIA Life's Insurance Advisor/Intermediary/ branch.
6Health Buddy Cancer Care is a complementary wellness program that helps in preventive care through holistic health management. For more details, please refer to Health buddy wellness page.
7On Major Cancer diagnosis, the insured has the option to receive the guaranteed lumpsum benefit as Income or Lumpsum plus income up to 5 years. For more details please refer Sampoorna Care Brochure.
Tata AIA Life Insurance Company Limited is only the name of the Insurance Company & Tata AIA Health Pro is only the name of the Unit Linked health Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns.
The fund is managed by Tata AIA Life Insurance Company Ltd.
For more details on risk factors, terms and conditions please read Sales Brochure carefully before concluding a sale. The precise terms and condition of this plan are specified in the Policy Contract.
Past performance is not indicative of future performance. Returns are calculated on an absolute basis for a period of less than (or equal to) a year, with reinvestment of dividends (if any).
All investments made by the Company are subject to market risks. The Company does not guarantee any assured returns. The investment income and price may go down as well as up depending on several factors influencing the market.
Please make your own independent decision after consulting your financial or other professional advisor.
Unit Linked Insurance products are different from the traditional insurance products and are subject to the risk factors. Please know the associated risks and the applicable charges, from your Insurance Agent or Intermediary or Policy Document issued by the Insurance Company.
Various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns. The underlying Fund's NAV will be affected by interest rates and the performance of the underlying stocks.
The performance of the managed portfolios and funds is not guaranteed, and the value may increase or decrease in accordance with the future experience of the managed portfolios and funds.
Premium paid in the Unit Linked Insurance Policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the Insured is responsible for his/her decisions.
Please know the associated risks and the applicable charges, from your insurance agent or the Intermediary or policy document issued by the Insurance Company.
Insurance cover is available under the product.
The products are underwritten by Tata AIA Life Insurance Company Ltd.
The plans are not a guaranteed issuance plan, and it will be subject to Company’s underwriting and acceptance.
For more details on risk factors, terms and conditions please read sales brochure carefully before concluding a sale.
All Premiums are subject to applicable taxes, cesses & levies which will entirely be borne by the Policyholder and will always be paid by the Policyholder along with the payment of Premium. If any imposition (tax or otherwise) is levied by any statutory or administrative body under the Policy, Tata AIA Life Insurance Company Limited reserves the right to claim the same from the Policyholder. Alternatively, Tata AIA Life Insurance Company Limited has the right to deduct the amount from the benefits payable by Us under the Policy.
Auto debit discount is applicable for Payments made through any electronic mode through an auto debit mandate for 1st-year instalment.
Risk cover commences along with policy commencement for all lives, including minor lives.
Buying a Health Insurance Policy is a long-term commitment. An early termination of the Policy usually involves high costs, and the Surrender Value payable may be less than the all the Premiums Paid.
In case of non-standard lives and on submission of non-standard age proof, extra premiums will be charged as per our underwriting guidelines.
Discount on policy will be subject to sales literature and policy contract.
To know more about the products, features, and eligibility, kindly visit our nearest branch or contact us at +91 22 6984 9300
L&C/Advt/2026/Nov/6219




 Get payment on diagnosis of any covered 57 critical illnesses