One time Investment Plans

A one-time investment plan is when an investor makes a single payment of the entire investment capital rather than making periodical payments.... Read more These plans assist individuals in growing their funds through market-linked5 investments, fixed income instruments, or government-backed savings schemes. One-time investment plans are widely used for achieving long-term financial goals. Read less
Grow your Wealth with Tax-free Returns3                                     

Neeraj Chopra
1756997995324

All funds rated 4 or 5 stars4

1756997995324

Zero LTCG tax2

1756997995324

Zero premium allocation charge

1756997995324

All Funds rated 4 or 5 stars

In this policy, the investment risk in investment portfolio is borne by the policyholder

315.40% is the 5-year CAGR of Tata AIA Multi Cap Fund as of Aug'26. Benchmark: 8.94%. T&C apply. Past performance is not indicative of future performance. The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.

Investment Calculator

Are you an NRI?

Yes
No

Gender

Male
Female

Do you smoke?

Yes
No

Please Enter Amount

Select date of birth first

Premier SIP Calculator

Unable to load your customized plan

Please try again after some time

Our sales representative will connect with you soon to assist further

Try again

Premier SIP Calculator

Request timeout

We're facing a technical issue. Please try again after some time

Try again
back button

Investment Calculator

Here’s your customised plan

Buy now Next arrow

Get Maturity Benefit

tooltip
  • 4% and 8% are assumed rates of return
  • 15.42% is the 5-year returns of Tata AIA Multi Cap Fund as of Mar'26 (Benchmark - Returns: 10.06% | Index: S&P BSE 200)
close image

As per assumed rate of return

₹34.57 Lakh

As per assumed rate of return

₹34.57 Lakh

by paying ₹19,983/month

Total premium: ₹11.99 Lakh

tooltip
  • 1st year premium (with discount): ₹9720/month
  • 2nd year onwards premium: ₹10,000/month
close image

Additional Benefits

tooltip
  • Life cover: Receive 100% of the Insured Amount upon first occurrence of terminal illness or in the unfortunate event of death, whichever happens first.
  • Accidental Death Cover: Receive payout in case of death due to accident
  • Accidental Total & Permanent Disability Cover: Receive payout if you’re permanently disabled due to an accident.
close image

Life Cover (including Terminal Illness Cover)

Accidental Death Cover

Accidental Total & Permanent Disability

Discount

Online discount
tooltip
close

Applicable if the policy is purchased digitally.
This discount is auto-applied and can't be removed

Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V01) and
Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V01). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually. Product option: Future Secure.

Almost there!

Your premium calculation is in progress

Success Icon

Success

Your details have been successfully submitted. A representative from Tata AIA Life Insurance will call you soon.

Failure Icon

Failure

Your details could not be saved.
Please try again.

Verify OTP

Kindly enter the OTP sent to

+91 736365432

Please enter valid OTP

01:60

Didn't receive OTP?

Technical issue detected - please continue without OTP verification

What is a one-time investment plan?

A one-time investment plan is an investment approach where a lump sum amount is invested at one time rather than through regular contributions. It may involve insurance-linked products, mutual funds, fixed-income instruments or other investment avenues, depending on the investor's financial objectives and risk tolerance.
 

In a lump sum investment, the entire amount is committed upfront. The money may then remain invested for a defined period, with the value depending on the chosen product, applicable returns, charges and market performance.
 

A one-time investment may be considered when an individual has surplus funds from sources such as a bonus, inheritance, maturity proceeds or accumulated savings. The investment horizon and liquidity requirement need to be assessed before committing the amount.
 

For insurance-linked options, a single premium may provide life insurance coverage along with a savings or investment component, depending on the policy structure. Market-linked products carry investment risk, while products offering guaranteed returns provide benefits according to their specified terms and conditions.

Best lump sum investment options

The appropriate lump sum investment option depends on the investment horizon, financial goals, liquidity requirements and tolerance for risk. Some commonly considered avenues include:

  • Equity Funds

    • Equity funds mostly include investments in the equity of listed companies.
    • Such funds are operated by highly skilled fund managers.
    • They are typically safer than individual stock investments.
    • Such funds help in achieving diversification.
    • They are good for wealth accumulation in the long run.
    • ELSS funds also offer tax2 exemptions under Section 80C of Income Tax Act, 1961.
    • Such funds can give potentially higher returns in the long run.
  • Debt Funds

    • Debt funds invest in government securities and highly rated corporate bonds.
    • They are considered less risky than equity and hybrid funds.
    • These funds aim to provide stable and reliable returns.
    • Debt funds are suitable for conservative investors.
    • They may also offer tax efficient returns based on the holding period.
    • These funds are commonly used for medium-term financial goals.
  • Liquid Funds

    • Liquid funds invest in short-term and low-risk debt instruments.
    • They are suitable for short-term investments of up to one year.
    • These funds offer high liquidity and easy access to money.
    • They generally provide more stable returns than regular savings accounts.
    • Liquid funds have lower expense ratios, which reduces investment costs.
    • Investors can easily switch funds to other investment products.
  • Unit Linked Insurance Plans (ULIPs)

    • ULIPs combine life insurance coverage with market-linked5 investments.
    • A part of the premium provides insurance protection.
    • The rest is invested in equities, debt, or balanced funds.
    • ULIPs give the flexibility to shift among various types of funds as per their financial objectives.
    • Partial withdrawal is possible only after the completion of the lock-in period.
    • Tax2 benefits under Section 80C of the Income Tax Act are available in case of ULIPs.
    • The maturity value of ULIP can avail tax rebates as per Section 10(10D).
  • Fixed Deposits

    • Fixed Deposits are among the most trusted investment options in India.
    • They provide guaranteed returns for a fixed tenure.
    • Interest rates remain fixed and are not affected by market fluctuations.
    • Senior citizens generally receive higher interest rates.
    • Fixed deposits are suitable for low-risk investors.
    • Many banks also offer automatic renewal and partial withdrawal facilities.
  • 5-Year Tax-Saving Fixed Deposits

    • These deposits provide tax benefits along with guaranteed returns.
    • Investments qualify for deductions2 under Section 80C of the Income Tax Act, 1961.
    • They come with a fixed lock-in period of five years.
    • Premature withdrawals are not allowed during the lock-in period.
    • Fixed interest rates help provide clarity on expected returns.
    • Senior citizens may receive higher interest rates.
  • Public Provident Fund (PPF)

    • PPF is a government-backed long-term savings scheme.
    • It provides stable and guaranteed returns.
    • Returns are not directly affected by market movements.
    • The minimum investment tenure is 15 years.
    • The account can be extended in blocks of five years.
    • Investments qualify for tax deductions under Section 80C.
    • Interest earned and maturity proceeds are tax-free, subject to prevailing tax rules.
    • Investors can also avail loan facilities after specific years of investment.
    • A nomination facility is available.
  • Pension Plans

    • Pension plans help create regular income after retirement.
    • Single premium pension plans allow investors to make a one-time lump sum investment.
    • These plans provide monthly, quarterly, or yearly payouts.
    • Investors can choose immediate or deferred pension options.
    • Income may continue for life or for a fixed period.
    • Some pension plans also offer spouse coverage benefits.
    • Tax2 benefits may be available under Section 80CCC of the Income Tax Act.
  • Gold Assets

    • Gold is commonly considered a hedge against inflation.
    • It usually has low correlation with equity and debt investments.
    • Gold investments offer high liquidity.
    • Investors can easily buy or sell gold when required.
    • Gold often performs well during economic uncertainty.
    • It is widely used for portfolio diversification.
    • Although prices may fluctuate in the short term, gold has shown long-term growth potential over time.
  • Sukanya Samriddhi Yojana (SSY)

    • SSY is a government-backed savings scheme for a girl child.
    • It helps parents create a corpus for education and marriage expenses.
    • The scheme offers attractive interest rates revised periodically by the government.
    • Investments qualify for tax deductions under Section 80C.
    • Partial withdrawals are allowed for higher education and marriage expenses, subject to conditions.
    • Maturity proceeds are tax-free.
    • SSY is considered a reliable long-term savings option for families.
  • National Pension System (NPS)

    • NPS is a government-backed retirement savings scheme.
    • It helps investors build a retirement corpus through market-linked investments.
    • Investors can choose between Active Choice and Auto Choice investment options.
    • The scheme offers flexibility in contribution amount and frequency.
    • Tax2 benefits are available under Sections 80C and 80CCD of the Income Tax Act, 1961.
    • A part of the corpus can be withdrawn after retirement.
    • The remaining amount is generally used to purchase an annuity for pension income.

How does a one-time investment plan work?

A one-time investment involves investing a lump sum amount into a chosen financial product instead of making regular contributions. Once invested, the amount remains in the selected avenue for the applicable tenure, with returns or benefits depending on its structure and performance.

Investment Amount

The process begins with determining the amount available for investment. The investor may consider surplus capital, existing financial commitments, emergency reserves and the period for which the money can remain invested.

Financial Goals

The investment amount is then linked to specific financial goals, such as retirement, children's education, wealth creation or a planned major expense. The time horizon can influence the choice of investment avenue.

Investment Option

The available investment options are assessed based on factors such as risk, liquidity, tenure, expected returns and product structure. Insurance-linked options may combine life cover with an investment or savings component, subject to policy terms.

Lump Sum Contribution

Once an option is selected, the investor makes the required upfront contribution. In an insurance product with a single premium, the premium is paid once according to the policy terms.

Investment Period

The invested amount remains in the selected product for the applicable tenure. In a market-linked plan, its value may rise or fall according to the performance of the underlying investments.

Investment Review

The investment can be reviewed periodically based on its performance, charges, asset allocation and progress towards the intended goal. The frequency and method of review depend on the product structure.

Investment Proceeds

At maturity or another permitted stage, the investor receives the applicable proceeds according to the product's terms. For insurance-linked products, the benefits may differ depending on the policy structure and whether maturity or death benefits become payable.

Tata AIA Best ULIP Plans

Solution Composition

Param Raksha Life Pro+ is designed for combination of benefits of following individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V02). Both products are also available for sale individually.

Tata AIA

Param Raksha Life Pro + 

  • Multicap fund delivered 15.40% returns (Benchmark: 8.94%)3
  • All funds rated 4 or 5 stars4 by Morningstar
  • Get high life cover to secure your family

Solution Composition

Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP, a non-participating, unit-linked, individual life insurance savings plan (UIN: 110L174V02), and Tata AIA Health Buddy, Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually.

Tata AIA

Premier SIP

  • No premium allocation charges
  • Generate second income with smart withdrawal strategies
  • Payouts are tax exempted11
Preview Arrow
Next Arrow

Who Needs a One Time Investment Plan?

Individuals with Surplus Funds

People who receive bonuses, inheritance amounts, or proceeds from property sales may use these plans to grow their money effectively.

Long-Term Investors

These plans are suitable for individuals’ planning retirement, children’s education, marriage expenses, or long-term wealth creation.

Conservative Investors

Risk-averse investors usually go for fixed deposits, debt funds, or government savings schemes to earn steady returns.

Tax-Saving Investors

Many one-time investment plans offer tax2 benefits, which can help reduce taxable income.

Retired Individuals

Retirees may use these plans to create regular income and maintain financial stability after retirement.

Advantages of One Time Investment Plans

Potential for High Returns

Market-linked5 investments such as equity funds and ULIPs may generate strong long-term growth.

Discipline and Convenience

A single investment reduces the need for regular contributions and simplifies financial planning.

Long-Term Growth

Long-term investments benefit from compounding, which helps investments grow steadily over time.

Goal Achievement

These plans help investors prepare for future financial goals in a structured manner.

Peace of Mind

Government-backed and fixed-income products provide stability and predictable returns.

Disadvantages of One-Time Investment Plans

Market Timing Risk

Investing a large amount during market highs may affect short-term returns if markets decline later.

Limited Liquidity

Some plans include lock-in periods that may restrict immediate access to funds.

Inflation Risk

Fixed-return investments may not always generate returns higher than inflation over the long term.

Lower Flexibility

Unlike SIPs, one-time investments do not allow staggered investments across different market levels.

Tax Implications

Some investment products may attract taxes2 on returns, interest income, or withdrawals based on prevailing tax rules.

Why Choose Tata AIA Life Insurance?

icon1

98 Lakh+

Families protected so far6

Rs 9,00,000 Crore+

#1 in Retail Sum Assured7

icon3

₹1.45 Lakh+ Crores

Assets Under Management8

icon4

99.45%

Individual Death Claim Settlement Ratio for FY25-269

icon5

600+ Branches

Presence across major cities in India

icon6

4 Hours

Express Claim Settlement10

7T&C apply

Factors Affecting Your One Time Investment Plan Decision

OTIPs offer an enticing path to growing your wealth. However, with a variety of options available, selecting the most suitable OTIP requires careful consideration. Several key factors influence this decision, ensuring your investment aligns perfectly with your financial goals and risk tolerance.

Let’s examine these factors that will help you make informed decisions and unlock the full potential of your OTIP.

Investment Goal

Are you saving for retirement, a child’s education, or a down payment on a house? Your goal will determine your risk tolerance and ideal investment horizon.

Risk Tolerance

How do you feel about the possibility of market fluctuations? Higher risk tolerance opens doors to potentially higher returns, while lower risk tolerance favours options like FDs.

Investment Horizon

When will you need the invested amount? Long-term goals benefit from growth-oriented options like equity mutual funds, while short-term goals might be better suited for FDs or liquid funds.

Features and benefits of one-time investment plans

A one-time investment combines an upfront contribution with a defined investment structure. Its features and benefits depend on the selected product and the terms governing it.

1

Upfront investment

The entire investment amount is committed at the beginning rather than being spread across monthly contributions.

  • Suitable for individuals with surplus capital.

  • Removes the need for recurring contributions towards the same investment.

  • The amount invested depends on the individual's available funds and financial objectives.

2

Potential for wealth creation

A long investment horizon may provide time for the invested amount and applicable returns to accumulate.

  • Returns depend on the selected investment avenue.

  • Market-linked investments may fluctuate with market conditions.

  • Reinvestment of returns, where permitted, may contribute to wealth creation over time.

3

Life insurance coverage

Certain insurance-linked one-time investment products combine investment or savings with life cover.

  • The nominee may receive a death benefit subject to policy conditions.

  • The extent of cover varies according to the product.

  • Life insurance needs can therefore be considered alongside investment objectives.

4

Tax benefits

Certain investments may provide tax2 benefits investment opportunities under applicable tax2 provisions.

  • Eligibility depends on the specific product and prevailing tax rules.

  • Deductions2 may have prescribed limits and conditions.

  • The taxation2 of maturity proceeds, withdrawals or other benefits can vary by product.

5

Choice between market-linked and defined benefits

Investors may encounter both market-linked and non-market-linked options when comparing one-time investments.

  • A market-linked plan exposes the investment value to the performance of its underlying assets.

  • Some savings products provide specified benefits according to their policy terms.

  • The distinction between these structures needs to be considered alongside the investor's risk tolerance and time horizon.

6

Liquidity considerations

Access to the invested amount depends on the product's withdrawal, surrender, maturity or exit conditions.

  • Some products may have lock-in periods.

  • Early withdrawal may be subject to conditions or charges.

  • Liquidity requirements need to be assessed before making the investment.

7

Alignment with financial goals

A one-time investment can be structured around a specific financial objective.

  • Retirement planning may require a longer investment horizon.

  • Education or major purchases may have defined target dates.

  • The investment avenue can be assessed according to the expected time available to reach the goal.

Conclusion

One-time investment schemes provide a convenient means to utilise extra money in ways that help one fulfil financial objectives. One can select investments that are tied to the market, have a fixed return, or are government-guaranteed according to one’s preferences. The objective could be to generate wealth, secure stable returns, receive periodic income, or save taxes. Selecting an appropriate investment method by considering various factors will lead to greater financial stability in the future.

1.

What’s another name for a one-time investment?

A one-time investment, also known as a lump sum investment, involves putting a larger amount of money into an investment option all at once. This differs from regularly scheduled contributions.

2.

What are the advantages of a one time investment?

Lump sum investments offer higher returns compared to investing a fixed amount regularly (SIPs). This is because you benefit less from rupee-cost averaging, where you buy units at different price points. They’re also easier to manage since you only invest once.

3.

Is a one-time investment better than an SIP?

The best option depends on your situation. Choose a lump sum if you have a sudden influx of cash and are comfortable with higher risk. Opt for SIPs if you prefer to invest gradually, benefit from averaging out costs, or don’t have a large sum available at once.

4.

How can I invest Rs. 10,000 with a lump sum?

You can consider mutual funds (explore equity or debt funds based on your risk tolerance), fixed deposits (FDs) for low-risk and steady returns, or gold as a way to hedge against inflation, though growth potential might be lower.

5.

Is there such a thing as a one-time SIP?

No, SIP stands for Systematic Investment Plan. By definition, it involves investing a fixed amount at regular intervals. A one-time investment wouldn’t be considered an SIP.

 
  • The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.

  • This advertisement is designed for combination of benefits of following individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V01). These products are also available for sale individually without the combination offered/ suggested. This benefit illustration is the arithmetic combination and chronological listing of combined benefits of individual products.

  • Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP, a non-participating, unit-linked, individual life insurance savings plan (UIN: 110L174V02), and Tata AIA Health Buddy, Non-participating, Non-Linked, Individual Health Product (UIN:110N183V01). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually

  • Param Raksha Life Pro+ is designed for combination of benefits of following individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V01). These products are also available for sale individually without the combination offered/ suggested.

  • 1As per the duly approved product design and terms & conditions of the product, Illustration shows a monthly premium of ₹15,000 for Tata AIA Premier SIP for a 25-year-old male, standard life, premium payment term: 10 years, policy term: 20 years with 100% investment in Tata AIA Multi Cap Fund in Future Secure plan option. 4% and 8% are assumed rates of return. 17.65% is the 5-year return as of April'26. Maturity amount: ₹24,15,144 at 4% returns, ₹43,78,331 at 8% returns and ₹ 1,73,67,190 at 17.65% returns. The fund value calculation is done by projecting the past returns of multi cap fund after adjusting for all expenses in Tata AIA Premier SIP. The above values have been calculated assuming 17.65% p.a.  CAGR, which is the past 5-year return of Multi Cap Fund as of April'26.

  • Some benefits are guaranteed, and some benefits are variable with returns based on the future performance of your insurer carrying on life insurance business. If your policy offers guaranteed benefits, then these will be clearly marked “guaranteed’ in the illustration table on this page. If your policy offers variable benefits, then the illustrations on these pages will show two different rates of assumed future investment returns. Currently these are assumed Rate of returns as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.

  • 2Income Tax benefits would be available, subject to fulfillment of conditions of aggregate premium within threshold limit of ₹2.50 Lakh/annum for ULIP and ₹5.0 Lakh/annum for non ULIP Life insurance and maintaining conditions of premium to sum assured ratio as stipulated therein in Section 11, Schedule II (erstwhile Section10(10D)) of Income Tax Act 2025. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implications mentioned anywhere on this site. Please consult your own tax consultant to know the tax benefits available to you.

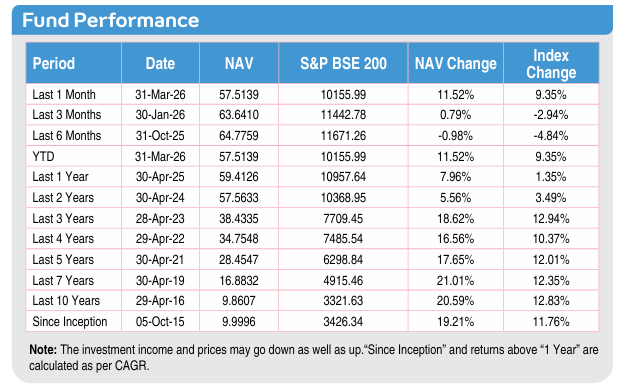
  • 35-year computed NAV for Multi Cap Fund as of April 2026. Other funds are also available. Benchmark of this fund is S&P BSE 200.
  • 4All funds open for new business which have completed 5 years since inception are rated 4 star or 5 star by Morningstar as of August 2025.

  • ©2025 Morningstar. All rights reserved. The Morningstar name is a registered trademark of Morningstar, Inc. in India and other jurisdictions. The information contained here: (1) includes the proprietary information of Morningstar, Inc. and its affiliates, including, without limitation, Morningstar India Private Limited (“Morningstar”); (2) may not be copied, redistributed or used, by any means, in whole or in part, without the prior, written consent of Morningstar; (3) is not warranted to be complete, accurate or timely; and (4) may be drawn from data published on various dates and procured from various sources and (5) shall not be construed as an offer to buy or sell any security or other investment vehicle. Neither Morningstar, Inc. nor any of its affiliates (including, without limitation, Morningstar) nor any of their officers, directors, employees, associates or agents shall be responsible or liable for any trading decisions, damages or other losses resulting directly or indirectly from the information.  

  • 5Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.

  • 698,01,699 families protected till 18th May 2026.

  • 7Retail Sum Assured for FY’25-26 is Rs 9,00,876 Crores

  • 8As on 31st March 2026, the company has a total Assets Under Management (AUM) of ₹1,45,589 Crore

  • 9Individual Death Claim Settlement Ratio is 99.45% for FY 2025-26 as per latest annual audited figures. 

  • 10Applicable to only non-early claims more than 3 years of policy duration, non-investigation cases, up to Sum assured of ₹50 Lakh. Applicable for branch walk in. Time limit to submit claim to Tata AIA by 2 pm (working days). Subject to submission of complete documents. Not applicable to ULIP policies and open title claims.

  • 11ULIP policies issued on or after 1st February 2021 if the amount of aggregate annual premium payable in the financial year for all such policies does not exceeds INR 2,50,000/-.  Subject to fulfillment of conditions mentioned in 10(10D).

  • For more details on risk factors, terms and conditions please read Sales Brochure carefully before concluding a sale. Insurance cover is available under this product.

  • Linked Life Insurance products are different from traditional insurance products and are subject to risk factors.

  • The premium paid in Linked Life Insurance policies is subject to investment risks associated with capital markets and publicly available index. The NAV of the units may go up or down based on the performance of Fund and factors influencing the capital market/publicly available index and the insured is responsible for his/her decisions.

  • Tata AIA Life Insurance Company Limited is only the name of the Life Insurance Company & Tata AIA Smart Sampoorna Raksha Supreme, Smart SIP are only the name of the Linked Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns.

  • Please know the associated risks and the applicable charges, from your insurance agent or the Intermediary or policy document issued by the insurance company.

  • The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns.

  • Past performance is not indicative of future performance.

  • L&C/Advt/2026/Jun/3790

crossImg

Looking to buy a new insurance plan?

Existing customer?

or

New user? Our experts are happy to help.

NRI?

+91

Thank you for sharing your details.

Our representative will contact you soon.