







Call us
Call us
 FOR EXISTING POLICY
Have query on premium, payout or any servicing need?
Call us:
 FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY (NRIs)
Note: Consent is provided to Tata AIA Life Insurance Company Limited to contact you by calling/giving missed call to the above numbers.
Thank you for sharing your details. To receive a call from Tata AIA Financial Advisor.
reCAPTCHA is not working.
No relevant search results found.
Popular searches
Continue from where you left of
A 25 lakh investment plan is a financial tool that helps you build a corpus of ₹25 lakh over a set period. This plan includes planned savings, supports... Read more major milestones, and includes life coverage for family security. Such planning supports disciplined contributions over time while preparing for future responsibilities with clarity and financial balance. Read Less
ULIP Calculator
ULIP Calculator
Here’s your customised plan
Get Maturity Benefit
As per assumed rate of return
₹34.57 Lakh
As per assumed rate of return
₹34.57 Lakh
Total premium: ₹11.99 Lakh
Additional Benefits
Life Cover (including Terminal Illness Cover)
Accidental Death Cover
Accidental Total & Permanent Disability
Discount
Applicable if the policy is purchased digitally.
This discount is auto-applied and can't be removed
Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V01) and
Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V01). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually. Product option: Future Secure.
Your premium calculation is in progress

Kindly enter the OTP sent to
Please enter valid OTP
01:60
Didn't receive OTP?
Success
Your details have been successfully submitted. A representative from Tata AIA Life Insurance will call you soon.
Failure
Your details could not be saved.
Please try again.
A 25-lakh investment plan refers to a financial strategy for investing ₹25 lakh towards defined goals, such as generating income, building wealth, or planning for retirement. The amount can be allocated across one or more investment avenues based on the investor's time horizon, liquidity needs, and risk tolerance.
The choice of investment depends on whether the priority is regular income, capital preservation, long-term growth or a combination of these objectives. For example, fixed-income options may provide a defined interest income, while market-linked investments can have returns that fluctuate with market performance.
Before investing the entire amount, investors can assess how much income they need each month, how long the capital can remain invested and whether they need access to part of the money during the investment period.
After understanding what is a 25-lakh investment plan, let’s understand how it works:
A 25-lakh investment plan functions through regular premium contributions made over a selected tenure. Once the target amount and time horizon are set, the plan calculates suitable premiums. These funds are invested through traditional or market-linked7 methods under the chosen investment plan structure. Market-linked plans invest across equity and debt instruments, while traditional plans accumulate declared bonuses. Over time, compounding builds the corpus, with maturity benefits paid as a lump sum or income.
Investors looking to invest 25 lakhs for monthly income can consider different avenues based on their income requirement, risk tolerance, liquidity needs and investment horizon. No single option provides the same combination of income, capital protection and growth potential.
A bank fixed deposit can provide interest income at a rate determined at the time of investment. Some deposits offer monthly interest payouts, which can suit investors seeking a defined cash flow.
For example, at an annual interest rate of 7%, ₹25 lakh would generate ₹1.75 lakh in annual interest before tax2, equivalent to approximately ₹14,583 per month. The actual rate, payout structure, and applicable tax 2 treatment depend on the deposit terms.
Eligible investors can consider schemes such as the Post Office Monthly Income Scheme or Senior Citizens' Savings Scheme, subject to their respective eligibility, investment limits and prevailing rates.
These schemes can provide periodic income, although the payout frequency may not always be monthly. Investment limits may also prevent the entire ₹25 lakh from being placed in a single scheme.
A lump sum can be invested in a suitable mutual fund, with withdrawals planned through a Systematic Withdrawal Plan. The amount withdrawn each month can be set according to the investor's requirement.
However, the withdrawals are not fixed interest payments. The value of the investment and sustainability of withdrawals depend on fund performance, withdrawal amounts and the investment period.
Annuity products can provide periodic income according to the selected annuity option and policy terms. They may be considered when regular income is a key objective, particularly during retirement.
The payout, liquidity provisions, death benefits and other conditions vary across products, making the policy terms relevant before committing a large amount.
Some life insurance savings plans combine life cover with structured benefits over a defined policy term. Depending on the plan, benefits may include regular income or a maturity benefit, subject to the applicable policy terms.
For investors considering life insurance alongside income planning, Tata AIA has savings solutions such as Fortune Guarantee Plus and Fortune Guarantee Supreme, with options for regular income and other policy benefits. The available payout structure, premium requirements and eligibility depend on the selected plan.
A ULIP combines life insurance with a market-linked investment component. The investment portion is allocated to available funds, which may include equity, debt or hybrid funds, depending on the product.
Tata AIA offers ULIP products including Tata AIA Smart SIP and other ULIP-based solutions. Since these products are market-linked, their value can fluctuate with the performance of the underlying funds.
For an investor with ₹25 lakh, the amount allocated to a ULIP would depend on the product's premium structure, policy requirements, and the individual's broader financial plan. A lump sum should not be committed solely on the basis of projected returns.
The investment options for 25 lakh offer various benefits, some of which are as follows:
Many plans provide options to adjust contribution frequency or switch allocation preferences based on risk appetite. Some plans also allow additional contributions during higher income phases.
Systematic contributions combined with compounding support gradual corpus growth. Over longer durations, accumulated returns contribute significantly towards achieving the ₹25 lakh objective.
A 25 lakh investment plan includes life coverage that supports family finances during uncertain situations. This structure ensures planned financial objectives stay protected even if unexpected events occur.
Under current income tax provisions, premiums may qualify for tax deductions under Section 80C, while maturity proceeds may qualify under Section 10(10D), subject to applicable conditions.
Tax 2 can affect the amount an investor retains after receiving interest, withdrawals or other investment proceeds. The tax 2 treatment depends on the investment product, type of income, holding period and applicable tax 2 provisions. The Income Tax Department's current guidance separately recognises interest, dividend and capital gains as different categories of income.
Consider the following while investing in an investment plan for 25 lakh:
Define short-term and long-term goals clearly. The investment duration should align with expected milestones such as education funding or retirement preparation.
Review historical performance trends of similar savings plans. While past outcomes do not predict future results, consistency offers insight into plan behaviour.
Assess the required life coverage by calculating human life value. The selected plan should support family financial needs if the policyholder is not present.
Compare plans across insurers by reviewing charges, policy features, claim settlement ratio, and long-term stability before making a decision.
Investing ₹25 lakh for regular income requires attention to both current cash-flow needs and the long-term value of the capital. The following mistakes can affect the sustainability of the income plan.
A 25 lakh investment plan supports disciplined savings while combining insurance coverage within a single structure. It may suit individuals planning long-term financial goals with defined timelines. Careful evaluation of coverage needs, duration, and plan structure helps ensure the chosen plan aligns with personal responsibilities and future financial preparation.
1.
Returns depend on the plan structure. Market-linked plans7 vary with markets, while traditional plans offer declared additions over the policy duration.
2.
Tax benefits are subject to the provisions of the Income-tax Act, 1961 and prevailing tax laws. Eligibility for tax benefits may vary depending on the taxpayer's applicable tax regime and individual circumstances
3.
A ₹25 lakh investment plan includes life insurance coverage, supporting family finances during unforeseen events while savings continue as planned.
4.
Yes, this plan suits long-term goals, as longer durations support accumulation through reinvested returns and structured contributions.
5.
Yes, the best investment plan for 25 lakhs depends on factors such as your income needs, investment horizon, liquidity requirements and risk tolerance.
The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.
Premier SIP is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Life Insurance Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V02) and (2) Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Product option: Future Secure These products are also available for sale individually without the combination offered/suggested.
Param Raksha Life Pro+ is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V01). These products are also available for sale individually without the combination offered/suggested.
Some benefits are guaranteed, and some benefits are variable with returns based on the future performance of your insurer carrying on life insurance business. If your policy offers guaranteed benefits, then these will be clearly marked “guaranteed’ in the illustration table on this page. If your policy offers variable benefits, then the illustrations on these pages will show two different rates of assumed future investment returns. Currently the gross investment returns are stipulated as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.
2Income Tax benefits would be available as per the prevailing income tax laws, subject to fulfillment of conditions stipulated therein. Income Tax laws are subject to change from time to time. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implication mentioned anywhere in this document. Please consult your own tax consultant to know the tax benefits available to you. No Goods and Service Tax shall be applicable on Individual life insurance products as per prevailing laws.
3All funds open for new business which have completed 5 years since inception are rated 4 or 5 Star by Morningstar as of August 2025.
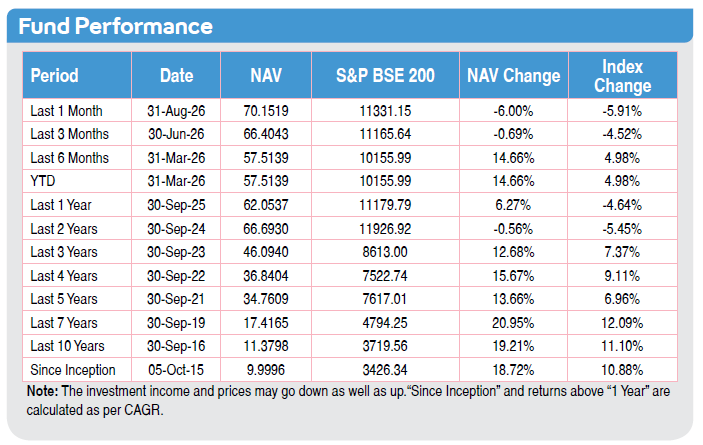
45-year computed NAV for Multi Cap Fund as of September 2026. Other funds are also available. Benchmark of this fund is S&P BSE 200.
5©2025 Morningstar. All rights reserved. The Morningstar name is a registered trademark of Morningstar, Inc. in India and other jurisdictions. The information contained here: (1) includes the proprietary information of Morningstar, Inc. and its affiliates, including, without limitation, Morningstar India Private Limited (“Morningstar”); (2) may not be copied, redistributed or used, by any means, in whole or in part, without the prior, written consent of Morningstar; (3) is not warranted to be complete, accurate or timely; and (4) may be drawn from data published on various dates and procured from various sources and (5) shall not be construed as an offer to buy or sell any security or other investment vehicle. Neither Morningstar, Inc. nor any of its affiliates (including, without limitation, Morningstar) nor any of their officers, directors, employees, associates or agents shall be responsible or liable for any trading decisions, damages or other losses resulting directly or indirectly from the information.
6The Insured Amount under Terminal Illness with Term Booster option (in Health Buddy) is payable on earlier of death or diagnosis of Terminal illness of the Life Insured. Please refer Terms and Conditions for more details.
7Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.
Linked Life Insurance products are different from traditional insurance products and are subject to risk factors.
The premium paid in Linked Life Insurance policies is subject to investment risks associated with capital markets and publicly available index. The NAV of the units may go up or down based on the performance of Fund and factors influencing the capital market/publicly available index and the insured is responsible for his/her decisions.
The fund is managed by Tata AIA Life Insurance Company Ltd. (hereinafter the “Company”). Tata AIA Life Insurance Company Limited is only the name of the Insurance Company & Tata AIA Smart SIP is only the name of the Unit Linked Life Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns.
Please know the associated risks and the applicable charges, from your insurance agent or the Intermediary or policy document issued by the insurance company.
The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns.
Buying a Life Insurance policy is a long-term commitment. An early termination of the policy usually involves high costs, and the Surrender Value payable may be less than the all the Premiums Paid.
Insurance cover is available under the product. For more details on risk factors, terms and conditions please read sales brochure carefully before concluding a sale.
L&C/Advt/2026/Oct/5928




 Multicap fund delivered 13.66% returns (Benchmark: 6.96%)4