₹35 Lakh Investment Plan in India

A 35 lakh investment plan in India is an effective scheme to save adequate money and fulfil your financial objectives. It also provides the additional ... Read more benefit of life insurance, which will ensure your family's future financially in your absence. When unexpected circumstances like medical emergencies or losses of jobs take place, it helps in providing cover for such situations. Read Less

Grow your Wealth with Tax-free2 Returns

Investment Plans Banner Image
img
1756997995324

Wealth creation + Life Cover

1756997995324

All funds rated 4 or 5 stars3

1756997995324

Zero premium allocation charge

In this policy, the investment risk in investment portfolio is borne by the policyholder

45-year CAGR for Multi Cap Fund as of Nov'25. Benchmark: 16.65%. Life cover included. T&C apply. Past performance is not indicative of future performance. The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.

ULIP Calculator

Are you an NRI?

Yes
No

Gender

Male
Female

Do you smoke?

Yes
No

Please Enter Amount

Select date of birth first

Premier SIP Calculator

Unable to load your customized plan

Please try again after some time

Our sales representative will connect with you soon to assist further

Try again

Premier SIP Calculator

Request timeout

We're facing a technical issue. Please try again after some time

Try again
back button

Ulip Calculator

Here’s your customised plan

Buy now Next arrow

Get Maturity Benefit

tooltip
  • 4% and 8% are assumed rates of return
  • 15.42% is the 5-year returns of Tata AIA Multi Cap Fund as of Mar'26 (Benchmark - Returns: 10.06% | Index: S&P BSE 200)
close image

As per assumed rate of return

₹34.57 Lakh

As per assumed rate of return

₹34.57 Lakh

by paying ₹19,983/month

Total premium: ₹11.99 Lakh

tooltip
  • 1st year premium (with discount): ₹9720/month
  • 2nd year onwards premium: ₹10,000/month
close image

Additional Benefits

tooltip
  • Life cover: Receive 100% of the Insured Amount upon first occurrence of terminal illness or in the unfortunate event of death, whichever happens first.
  • Accidental Death Cover: Receive payout in case of death due to accident
  • Accidental Total & Permanent Disability Cover: Receive payout if you’re permanently disabled due to an accident.
close image

Life Cover (including Terminal Illness Cover)

Accidental Death Cover

Accidental Total & Permanent Disability

Discount

Online discount
tooltip
close

Applicable if the policy is purchased digitally.
This discount is auto-applied and can't be removed

Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V01) and
Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V01). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually. Product option: Future Secure.

Verify OTP

Kindly enter the OTP sent to

+91 736365432

Please enter valid OTP

01:60

Didn't receive OTP?

Technical issue detected
please continue without OTP verification

Almost there!

Your premium calculation is in progress

What is a ₹35 lakh investment plan?

The 35 lakh investment plan in India scheme refers to the financial plan through which one aims to save or invest 35 lakhs. This could be an investment in mutual funds, stocks, property, or a combination of these for specific financial purposes at a particular time period. The 35 lakh investment plan helps to save and accumulate wealth for achieving specific financial purposes.

How does a ₹35 lakh investment plan work?

Here’s how investment plans for 35 lakh work:

  • In a 35 lakh savings plan, premiums are usually paid consistently over the course of the policy.
  • Premiums are directed to the insurance provider, where interest is earned and reinvested into the policy, leveraging compound interest.
  • Ultimately, accumulated returns help policyholders achieve their financial goals.
  • Additionally, a 35 lakh investment plan includes life insurance coverage.
  • The payout will be paid to your beneficiaries or heirs in the event of your death during the policy period.

Popular Tata AIA Investment Plans

Combination composition

Premier SIP is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Life Insurance Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V02) and (2) Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Product option: Future Secure These products are also available for sale individually without the combination offered/suggested.

Tata AIA

Premier SIP

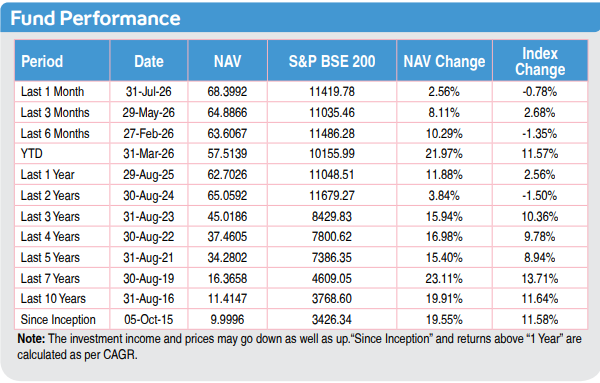
  • Multicap fund delivered 15.40% returns (Benchmark:8.94%)4
  • All funds rated 4 or 5 stars3 by Morningstar5
  • Payouts are tax2 exempted

Combination composition

Param Raksha Life Pro+ is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V02). These products are also available for sale individually without the combination offered/suggested.

Tata AIA

Param Raksha Life Pro + 

  • Multicap fund delivered 15.40% returns (Benchmark:8.94%)4
  • All funds rated 4 or 5 stars3 by Morningstar5
  • Get terminal illness cover with Term booster6 + high life cover
Preview Arrow
Next Arrow

Why should you buy a ₹35 lakh investment plan?

The key reasons for buying a 35 lakh investment plan are:

  • Helps you build a large corpus of ₹35 lakh for important life goals
  • Useful for home purchase, children’s education, business plans, or retirement.
  • Encourages disciplined and regular saving
  • Benefits from long-term compounding, helping money grow faster
  • Offers financial security for your family in case of emergencies (in insurance-linked plans)
  • Many plans include life cover along with investment
  • Provides tax2 benefits under Section 80C and sometimes tax-free maturity under Section 10(10D)
  • Allows flexible premium payment options (monthly, yearly, limited pay)
  • Can be customised based on your income, risk appetite, and goals
  • Reduces dependence on loans for major expenses
  • Give peace of mind by preparing you financially for the future

Benefits of a ₹35 lakh investment plan

The ₹35 lakh investment plan in India offers many benefits, some of which are as follows:

  1. Future financial security


    A ₹35 lakh savings plan can form part of a long-term financial strategy when the target amount is linked to specific future requirements. The accumulated corpus may be directed towards goals such as retirement, children's education or major purchase.
    Key considerations include:
    • Building a financial reserve: Regular contributions towards a defined target may create a financial reserve for future requirements.
    • Planning for major goals: A ₹35 lakh corpus may be earmarked for education, retirement, home purchase or other planned expenses.
    • Preparing for unforeseen needs: Maintaining long-term savings alongside suitable protection may provide financial support during unexpected circumstances.
    • Aligning savings with time horizon: The contribution amount and investment period can be assessed according to when the intended financial goal is expected to arise.
  2. Wealth accumulation through compounding


    Compounding refers to earning returns on the accumulated amount, including previously earned returns, where the product structure provides for such accumulation. Over a longer period, this can contribute to the projected value of savings.
    A 35 lakh investment plan with returns may benefit from compounding when returns are reinvested and the investment remains aligned with the chosen time horizon.
    The following factors influence the outcome:
    • Investment duration: A longer investment horizon gives accumulated returns more time to contribute to the corpus.
    • Regular contributions: Consistent contributions may build the invested amount gradually, depending on the terms of the chosen product.
    • Rate of return: The projected corpus depends on the applicable or assumed rate of return. Market-linked products do not provide fixed returns.
    • Reinvestment: Where returns are reinvested, the accumulated amount may participate in subsequent return calculations, subject to the product structure.
  3. Tax planning advantages


    Tax2 treatment can vary according to the financial product, premium structure, policy terms and applicable tax2 provisions. Therefore, tax2 benefits associated with a ₹35 lakh savings plan need to be assessed in the context of the specific product selected.
    Consider the following aspects:
    • Eligible tax deductions: Certain life insurance premiums may qualify for deductions2 under applicable provisions, subject to prescribed conditions and limits.
    • Tax treatment of benefits: The taxation of maturity or other policy benefits depends on the product and the applicable provisions at the relevant time.
    • Premium conditions: Eligibility for certain tax2 benefits may depend on factors such as premium amount, sum assured and policy structure.
    • Changing tax rules: Tax2 provisions may be amended, making it necessary to refer to the provisions applicable to the relevant financial year.
  4. Financial flexibility and fund switching


    Some market-linked savings products provide a choice of investment funds and may include fund-switching facilities. This gives policyholders scope to alter their fund allocation within the options permitted by the policy.
    Fund switching may involve:
    • Changing fund allocation: Policyholders may shift between available funds based on their financial objectives and risk tolerance.
    • Responding to financial priorities: The allocation can be reviewed when the intended investment horizon or financial priorities change.
    • Understanding fund options: Different funds may have different asset allocations, risk levels and return potential.
    • Checking policy conditions: The number of permitted switches, charges and other conditions depend on the specific policy.
  5. Life insurance coverage included


    A savings-oriented life insurance plan may combine a savings or investment component with life insurance coverage. The nature and extent of protection depend on the specific policy terms.
    Key aspects include:
    • Life cover: A death benefit may be payable to the policyholder's nominee or beneficiaries, subject to the policy conditions.
    • Financial protection: The insurance component can provide financial support to dependants if the life assured dies during the policy term..
    • Policy structure: The relationship between the savings component and life cover varies across different insurance products.
    • Reviewing coverage: The level of life cover may be assessed alongside existing policies and the financial needs of dependants.

What to consider when investing in a 35-lakh savings plan

Choosing a ₹35 lakh savings plan involves assessing the purpose of the investment, the expected time horizon and the structure of the chosen product. Before committing funds, consider the following factors:

1

Financial goals and investment horizon

Start by defining why the ₹35 lakh corpus is being planned and when it may be required.

  • Short-term goals: Consider whether the money is intended for a major expense within a relatively short period.

  • Long-term goals: Retirement, children's education or wealth accumulation may require a longer investment horizon.

  • Target amount: Assess the contribution required to work towards the ₹35 lakh target within the intended period.

2

Product features and benefits

Different savings and investment products have different structures, benefits and conditions.

  • Life insurance cover: Certain savings-oriented insurance products include life cover alongside their savings or investment components.

  • Additional benefits: Some products may include features such as bonuses, loyalty additions or withdrawal facilities, subject to policy terms.

  • Fund options: Market-linked products may provide access to different funds with varying asset allocations and risk levels.

3

Risk and return considerations

The relationship between risk, return and investment duration needs consideration before selecting a product.

  • Market-linked products: Returns depend on market performance and are not fixed.

  • Assumed returns: Projections shown in illustrations may be based on specified assumptions and should not be treated as actual future returns.

  • Risk tolerance: The level of investment risk needs to correspond with the investor's financial circumstances and time horizon.

4

Charges and other costs

Costs associated with savings or investment product can affect the amount that ultimately accumulates.

  • Policy charges: Insurance-linked products may have charges specified in the policy terms.

  • Transaction or fund charges: Certain investment products may have costs linked to transactions or fund management.

  • Withdrawal or exit costs: Check whether charges or conditions apply when funds are withdrawn or the policy is surrendered.

5

Liquidity and withdrawal conditions

The ability to access funds depends on the product structure and applicable conditions.

  • Withdrawal rules: Check when partial or full withdrawals are permitted.

  • Lock-in requirements: Certain products may have a specified lock-in period before withdrawals are permitted.

  • Emergency requirements: Consider whether sufficient funds remain available outside the ₹35 lakh investment target for unexpected expenses.

6

Institution and policy terms

The financial institution and specific product terms need to be assessed before investing.

  • Financial position: Review publicly available information about the institution's financial position and regulatory status.

  • Policy documentation: Read the benefit structure, exclusions, charges, surrender conditions and other applicable terms.

  • Service provisions: Check the processes available for premium payments, fund management, withdrawals and policy servicing.

7

Tax treatment

Tax2 implications can affect the net value of a ₹35 lakh savings plan.

  • Premium-related benefits: Certain premiums may qualify for tax2 deductions, subject to applicable provisions and limits.

  • Maturity benefits: Tax2 treatment of maturity proceeds depends on the product and prevailing tax rules.

  • Applicable conditions: Tax2 benefits may depend on factors such as policy structure, premium amounts and eligibility requirements.

Conclusion

A ₹35 lakh investment plan can help create wealth and financial security over the long term. You not only build a substantial corpus for your life goals but also protect your family financially through life insurance. Selecting the right plan after carefully evaluating your goals, benefits, costs, flexibility, and the credibility of the provider can maximise returns. The best investment plan for 35 lakhs improves disciplined saving, financial stability, and peace of mind.

1.

How to invest 35 lakhs in India?

The 35 lakhs can be invested in India using a variety of investment tools like mutual funds, stocks, or real estate.

2.

Can I opt for a 35 lakh investment plan with a fixed interest rate?

If you want to invest 35 lakhs with a fixed interest rate, you can explore fixed deposit schemes and other fixed-income instruments.

3.

Does a 35 lakh investment plan offer tax benefits?

The 35 lakh investment plan tax benefit may differ depending on the kind of investment in the 35 lakh plan, such as equity-linked savings plans.

4.

Can I monitor the performance of my investments within a 35 lakh plan?

Many investment platforms provide tools for monitoring the performance of investments within a 35 lakh plan.

5.

Is it possible to adjust my investment strategy within a 35 lakh investment plan?

With a 35 lakh investment plan, you can adjust your investment strategy based on the flexibility of the investment instruments you select.


  • The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.

  • Premier SIP is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Life Insurance Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V02) and (2) Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Product option: Future Secure These products are also available for sale individually without the combination offered/suggested.

  • Param Raksha Life Pro+ is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V02). These products are also available for sale individually without the combination offered/suggested.

  • If your policy offers variable benefits, then the illustrations on this page will show two different rates of assumed future investment returns. Currently the gross investment returns are stipulated as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.

  • 2Income Tax benefits would be available, subject to fulfillment of conditions of aggregate premium within threshold limit of ₹2.50 Lakh/annum for ULIP and ₹5.0 Lakh/annum for non ULIP Life insurance and maintaining conditions of premium to sum assured ratio as stipulated therein in Section 11, Schedule II (erstwhile Section10(10D)) of Income Tax Act 2025. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implications mentioned anywhere on this site. Please consult your own tax consultant to know the tax benefits available to you.

  • No Goods and Service Tax shall be applicable on Individual life insurance products as per prevailing laws

  • 3All funds open for new business which have completed 5 years since inception are rated 4 or 5 Star by Morningstar as of December 2025.

  • 5©2025 Morningstar. All rights reserved. The Morningstar name is a registered trademark of Morningstar, Inc. in India and other jurisdictions. The information contained here: (1) includes the proprietary information of Morningstar, Inc. and its affiliates, including, without limitation, Morningstar India Private Limited (“Morningstar”); (2) may not be copied, redistributed or used, by any means, in whole or in part, without the prior, written consent of Morningstar; (3) is not warranted to be complete, accurate or timely; and (4) may be drawn from data published on various dates and procured from various sources and (5) shall not be construed as an offer to buy or sell any security or other investment vehicle. Neither Morningstar, Inc. nor any of its affiliates (including, without limitation, Morningstar) nor any of their officers, directors, employees, associates or agents shall be responsible or liable for any trading decisions, damages or other losses resulting directly or indirectly from the information.

  • 4Data from our Tata AIA fund fact sheet shows the performance of Tata AIA Multi Cap fund & SFIN NO: ULIF 060 15/07/14 MCF110 as on August 2026. Benchmarked with Nifty 50. 
  • 6The Insured Amount under Terminal Illness with Term Booster option (in Health Buddy) is payable on earlier of death or diagnosis of Terminal illness of the Life Insured. Please refer Terms and Conditions for more details. 

  • The premium paid in Unit Linked Life Insurance policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the insured is responsible for his/her decisions. The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns. On survival to the end of the policy term, the Total Fund Value including Top-Up Premium Fund Value valued at applicable NAV on the date of Maturity will be paid

  • The fund is managed by Tata AIA Life Insurance Company Ltd. (hereinafter the “Company”). Tata AIA Life Insurance Company Limited is only the name of the Insurance Company & Tata AIA Smart Sampoorna Raksha Supreme and Tata AIA Smart SIP is only the name of the Unit Linked Life Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns 

  • The investment income and price may go down as well as up depending on several factors influencing the market. Please know the associated risks and the applicable charges, from your Insurance Agent or the Intermediary or Policy Document issued by the Insurance Company. Please make your own independent decision after consulting your financial or other professional advisor. Returns are calculated on an absolute basis for a period of less than (or equal to) a year, with reinvestment of dividends (if any). All investments made by the Company are subject to market risks. The Company does not guarantee any assured returns

  • Buying a Life Insurance Policy is a long-term commitment. An early termination of the policy usually involves high costs, and the surrender value payable may be less than all the premiums paid. Unit Linked Life Insurance products are different from traditional insurance products and are subject to risk factors. 

  • Life Insurance cover is available under the product. For more details on risk factors, terms and conditions please read sales brochure carefully before concluding a sale. 

  • L&C/Advt/2026/Oct/5631