







Call us
Call us
 FOR EXISTING POLICY
Have query on premium, payout or any servicing need?
Call us:
 FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY (NRIs)
Note: Consent is provided to Tata AIA Life Insurance Company Limited to contact you by calling/giving missed call to the above numbers.
Thank you for sharing your details. To receive a call from Tata AIA Financial Advisor.
reCAPTCHA is not working.
No relevant search results found.
Popular searches
Continue from where you left of
Planning for a 2 lakh pension per month can help you work towards financial independence and maintain your lifestyle... Read more after retirement. Starting early, investing consistently, and choosing suitable retirement-focused investment options can help you build the corpus required for your income goals. Proper understanding of how to get 2 lakh pension per month often helps during times of need. A well-structured retirement plan helps you prepare for rising expenses, manage inflation, and create a more predictable source of income after retirement.. Read less

Kindly enter the OTP sent to
Please enter valid OTP
01:60
Didn't receive OTP?
Your premium calculation is in progress
Retirement Calculator
Here's your customized plan
Total Maturity Amount
4% and 8% are assumed rates of return
₹2.48 Lakh
If the corpus is converted into 100% Annuity,
get lifetime pension of
₹19,387/month
₹1.81 Lakh
If the corpus is converted into 100% Annuity,
get lifetime pension of
₹14,219/month
Tata AIA Smart Pension Secure (UIN: 110L182V09) - Non-Participating, Unit Linked, Individual Life Insurance Pension Plan
Building a retirement corpus capable of generating a 2 lakh pension per month requires discipline, long-term planning, and a diversified investment strategy. While the required corpus may vary based on returns and retirement duration, following these steps can help you move closer to your retirement income goal.
Beginning your retirement planning early gives your investments more time to benefit from compounding. A longer investment horizon can reduce the monthly amount you need to invest while increasing your chances of building a larger retirement corpus.
As your income grows, try to increase your retirement contributions periodically. Regular step-ups can accelerate wealth creation and make it easier to achieve a higher monthly pension without relying on large investments later in life.
Avoid depending on a single investment option. A balanced portfolio of retirement plans, NPS, mutual funds, debt instruments, annuity plans, and other suitable assets can help manage risk while supporting long-term growth.
Pension and annuity plans can provide a predictable income after retirement. Combining these plans with market-linked3 investments may help create both long-term wealth and a regular retirement income stream.
Several retirement-oriented investments may offer tax4 benefits under applicable provisions of the Income Tax Act, subject to prevailing tax laws and the chosen tax regime. These savings can be redirected towards strengthening your retirement corpus.
Your financial goals, income, and expenses are likely to change over time. Reviewing your portfolio periodically allows you to rebalance investments and ensure they continue to align with your retirement objectives.
The purchasing power of money reduces over time due to inflation. Estimating future living expenses before deciding your retirement target can help you build a corpus that supports your lifestyle for many years after retirement.
Non-Participating, Unit Linked, Individual Life Insurance Pension Plan
(UIN: 110L182V09)
Non-Linked Non-Participating Individual Life Insurance Plan
(UIN:110N161V13)
Choosing suitable retirement products is equally important when planning for a 2 lakh pension per month. High-value pension plans can help you accumulate a substantial retirement corpus while offering different combinations of growth, protection, and guaranteed income.
Deferred annuity plans allow you to accumulate savings during your working years and start receiving regular pension payments after retirement. They are suitable for individuals planning a steady post-retirement income.
Retirement-focused ULIPs combine life insurance with market-linked3 investments. They offer the flexibility to invest according to your risk appetite while building long-term wealth for retirement.
Guaranteed5 income plans provide fixed payouts based on the policy terms. These plans may suit conservative investors looking for income certainty during retirement.
Endowment plans combine life cover with disciplined long-term savings. They provide a maturity benefit if the policyholder survives the policy term, helping create funds that may support retirement planning.
The National Pension System (NPS) is a government-regulated retirement scheme that invests across equity, corporate debt, and government securities. It can help build a sizeable retirement corpus through long-term, disciplined contributions.
Immediate annuity plans begin pension payouts shortly after a lump sum investment. They are generally considered by individuals who require regular income immediately after retirement rather than accumulating wealth over a longer period.
Building wealth steadily is an important part of planning for a 2 lakh pension per month. A disciplined investment approach, combined with regular reviews and suitable financial products, can help you create a retirement corpus that supports your long-term income needs.
Beginning your investments at a younger age gives your money more time to grow through compounding. This can reduce the monthly investment required while improving your long-term wealth creation potential.
Whenever your income increases, consider raising your retirement contributions as well. Even small annual increases can significantly strengthen your retirement corpus over the long term.
Spreading investments across equity, debt, retirement plans, annuities, and other suitable assets can balance growth opportunities with stability. Diversification may also reduce the overall impact of market fluctuations.
Your retirement strategy should evolve with your financial goals and changing market conditions. Reviewing your investments periodically allows you to rebalance your portfolio and stay aligned with your retirement objectives.
Inflation gradually increases the cost of living and reduces purchasing power. Factoring future expenses into your retirement planning can help ensure your savings continue to support your lifestyle after retirement.
Avoid making investment decisions based solely on short-term market movements. Remaining invested through different market cycles can improve the potential for long-term wealth creation.
Generating a 2 lakh pension per month requires building a sizeable retirement corpus before you retire. The exact amount depends on factors such as your retirement age, expected investment returns, inflation, annuity rates, and the number of years you expect your retirement income to last.
For many investors, a retirement corpus of approximately ₹4.5 crore to ₹6 crore may be required to support a monthly income of around ₹2 lakh, depending on withdrawal strategy and post-retirement returns. Building such a corpus generally requires starting early, investing consistently, and reviewing your financial plan regularly.
Using a retirement calculator can help estimate the corpus required based on your age, expected returns, monthly investments, and retirement goals.
| Current age | Investment period | Monthly investment | Assumed annual return | Estimated retirement corpus |
|---|---|---|---|---|
| 30 | 30 years | ₹22,000 | 12% | ₹6.2 crore |
| 35 | 25 years | ₹38,000 | 12% | ₹6.0 crore |
| 40 | 20 years | ₹65,000 | 12% | ₹5.9 crore |
| 45 | 15 years | ₹1,15,000 | 12% | ₹5.8 crore |
Illustrative estimates based on assumed long-term returns. Actual corpus and retirement income may vary depending on market performance, investment choices, inflation, annuity rates, and withdrawal strategy.
A larger retirement corpus provides flexibility to manage healthcare costs, inflation, and other post-retirement expenses. Reviewing your retirement plan periodically can help ensure you remain on track to achieve your desired retirement income.
Building a 2 lakh pension per month usually requires combining multiple investment options instead of depending on a single product. A diversified retirement portfolio can help balance growth potential, stability, and regular post-retirement income.
| Investment option | Risk level | Lock-in/tenure | Suitable for | Income potential |
|---|---|---|---|---|
| National Pension System (NPS) | Moderate | Till retirement | Long-term investors | Market-linked3 corpus with annuity |
| Pension annuity plans | Low | As per policy | Retirement income seekers | Guaranteed regular income |
| Retirement ULIPs | Moderate to High | Long term | Investors seeking growth with life cover | Market-linked |
| Hybrid mutual funds | Moderate | No mandatory lock-in | Long-term investors | SWP after retirement |
| Debt mutual funds | Low to Moderate | No mandatory lock-in | Conservative investors | Stable withdrawal option |
| Public Provident Fund (PPF) | Low | 15 years | Conservative long-term investors | Corpus accumulation |
| Employees' Provident Fund (EPF) | Low | Till retirement/withdrawal rules | Salaried individuals | Retirement corpus |
| Senior Citizens' Savings Scheme (SCSS) | Low | 5 years | Senior citizens | Regular interest income |
Subject to scheme terms and applicable regulations.
The National Pension System (NPS) is a government-regulated retirement scheme that invests across equity, corporate debt, and government securities. It helps create a retirement corpus through disciplined long-term contributions. At retirement, a portion of the corpus is generally used to purchase an annuity that provides regular pension income, while the remaining amount may be withdrawn as permitted under prevailing rules.
Pension annuity plans are designed to provide a regular income after retirement. Depending on the selected option, payouts may begin immediately or after an accumulation period. They can add stability to a retirement portfolio by offering predictable income.
Retirement ULIPs combine life insurance with market-linked investments. They allow long-term wealth creation while providing life cover during the policy term. Investors can usually choose between different fund options based on their financial goals and risk appetite.
Hybrid mutual funds invest in a mix of equity and debt instruments. This diversified allocation can help balance growth opportunities with comparatively lower volatility, making them suitable for long-term retirement planning.
Debt mutual funds primarily invest in fixed-income securities such as government securities, corporate bonds, and money market instruments. They may suit investors looking for relatively stable returns and lower portfolio volatility.
Public Provident Fund (PPF) is a government-backed long-term savings scheme with a 15-year tenure. It offers guaranteed returns declared by the Government from time to time and may form part of a diversified retirement strategy.
Employees' Provident Fund (EPF) helps salaried individuals accumulate retirement savings through regular contributions from both the employee and employer. The accumulated corpus can support long-term retirement planning.
The Senior Citizens' Savings Scheme (SCSS) is a government-backed savings scheme available to eligible senior citizens. It offers periodic interest payouts and may be considered by retirees seeking relatively stable post-retirement income.
The National Pension System (NPS) can play an important role in building a 2 lakh pension per month, provided you start investing early and contribute consistently. Since NPS is a market-linked retirement scheme, the final pension depends on factors such as your contribution amount, investment duration, asset allocation, annuity rates, and prevailing regulations at the time of retirement.
Beginning NPS contributions at a younger age gives your investments more time to grow through compounding. A longer investment horizon can help you accumulate a larger retirement corpus with comparatively lower monthly contributions.
Regular investments are essential for long-term corpus creation. Increasing your NPS contribution whenever your income rises can further strengthen your retirement savings and improve your potential pension.
NPS allows investors to allocate their contributions across equity, corporate debt, government securities, and alternative assets. Selecting an allocation that matches your age, financial goals, and risk appetite can help balance growth and stability over the long term.
Under the prevailing NPS withdrawal rules, a specified portion of the retirement corpus is generally used to purchase an annuity, which provides regular pension payments. The remaining eligible corpus may be withdrawn as a lump sum, subject to applicable regulations at retirement.
Your retirement goals and financial situation may change over time. Periodically reviewing your NPS investments allows you to rebalance your portfolio and ensure it remains aligned with your desired retirement income.
Starting your retirement planning early offers more than just additional investment years. It provides flexibility, allows your investments to compound over time, and can make it easier to build the corpus required for a 2 lakh pension per month benefits.
More time for compounding
The earlier you begin investing, the longer your money remains invested. This allows compounding to contribute significantly towards building a larger retirement corpus over the long term.
Lower monthly investment requirement
Starting early spreads your investment over a longer period. This generally reduces the monthly contribution needed compared to someone who begins investing closer to retirement.
Better ability to manage market fluctuations
Long-term investors usually have more time to recover from short-term market volatility. This can support more stable wealth creation through different market cycles.
Provides investment flexibility
A longer investment horizon allows you to diversify across different asset classes and gradually adjust your portfolio as your retirement approaches.
Helps manage inflation
Early retirement planning gives your investments a better opportunity to grow wealth to meet the rising living costs. This can help preserve your purchasing power during retirement.
Supports long-term financial security
Building a retirement corpus gradually through disciplined investing can reduce financial stress later in life and provide confidence in meeting future retirement expenses.
Our experts are happy to help you!
Our experts are happy to help you!
Planning for a 2 lakh pension per month becomes more structured when you use financial planning tools. These calculators can help estimate the retirement corpus you may need, compare investment options, and track your progress towards your retirement goals.
A Retirement Calculator helps estimate the corpus required to generate your desired retirement income. By entering details such as your current age, retirement age, monthly savings, and expected returns, you can understand whether your existing investment strategy is aligned with your goals.
A life insurance calculator helps estimate the level of financial protection your family may require. Choosing suitable life cover can protect your loved ones while allowing your retirement investments to remain focused on long-term wealth creation.
A term insurance calculator estimates premiums based on your age, coverage amount, policy term, and lifestyle factors. It helps you select affordable protection without affecting your retirement savings plan.
A ULIP calculator projects the potential value of your investments based on assumed returns, premium amount, and investment tenure. It can help you understand how market-linked3 investments may contribute towards your retirement corpus.
An annuity calculator estimates the regular income that a retirement corpus may generate after purchasing an annuity. Comparing different investment amounts can help you plan a suitable post-retirement income strategy.
An NPS calculator estimates the maturity corpus and expected pension based on your monthly contribution, investment period, and assumed returns. It helps you assess whether your current contributions are sufficient to meet your retirement objective.
A postal life insurance calculator provides estimated premiums and maturity values for eligible policies. It can help conservative investors understand how traditional savings-oriented insurance plans may support long-term financial planning.
Achieving a 2 lakh pension per month requires disciplined saving, long-term investing, and regular financial reviews. Starting early and building a diversified retirement portfolio can help you create the corpus needed for your retirement income goals. Using suitable retirement planning tools and reviewing your investments periodically can also help you stay prepared for changing financial needs and inflation over time.
1.
A combination of NPS, pension annuity plans, retirement ULIPs, mutual funds, and other retirement-focused investments may help you work towards a ₹2 lakh monthly pension, depending on your financial goals and risk appetite.
2.
The required retirement corpus depends on factors such as retirement age, expected returns, inflation, and withdrawal strategy. Many investors may require a corpus of around ₹4.5 crore to ₹6 crore to target this level of retirement income.
3.
Pension income is generally taxable according to the applicable income tax provisions. The tax4 treatment may vary depending on the source of the pension, the type of retirement product, and the prevailing tax laws at the time of receipt.
The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.
The complete name of Tata AIA Smart Pension Secure is Tata AIA Smart Pension Secure Non-Participating, Unit Linked, Individual Life Insurance Pension Plan (UIN: 110L182V09)
The complete name of Tata AIA Fortune Guarantee Pension is Tata AIA Life Insurance Fortune Guarantee Pension (UIN:110N161V13) - A Non-Linked, Non-Participating, Annuity Plan.
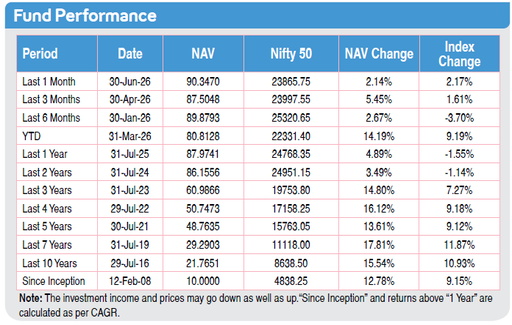
1Data from our TATA AIA fund factsheet shows the performance of TATA AIA Future Equity Pension fund & ULIF 020 04/02/08 FEP 110 as of May 2026. Benchmark of this fund is Nifty 50 -100%
2Partial withdrawals only available 3 times during the entire policy term and only for reasons specified in IRDA Regulations as amended from time to time
3Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.
4Income Tax benefits would be available as per the prevailing income tax laws, subject to fulfillment of conditions stipulated therein. Income Tax laws are subject to change from time to time. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implication mentioned anywhere in this document. Please consult your own tax consultant to know the tax benefits available to you.
No Goods and Service Tax shall be applicable on Individual life insurance products as per prevailing laws.
5The word Guaranteed, and Guarantee means the annuity payout is fixed at inception of the policy and will be payable for whole of life or till death of the Annuitant(s).
698,01,699 families protected till 18th May 2026
7Individual Death Claim Settlement Ratio is 99.45% for FY 2025-26 as per latest annual audited figures.
10Total Assets Under Management (AUM) as on 31st Mar’26 is ₹1,45,589 Crore.
9https://irdai.gov.in/document-detail?documentId=9311918. Retail Sum Assured for FY 2025-26 is ₹9,00,876 Crore.
10Applicable to only non-early claims with more than 3 years of policy duration, non-investigation cases, up to Sum assured of ₹50 Lakh. Applicable for branch walk in. Time limit to submit claim to Tata AIA Life Insurance by 2 pm (working days). Subject to submission of complete documents. Not applicable for ULIP policies and open title claims.
Some benefits are guaranteed, and some benefits are variable with returns based on the future performance of your insurer carrying on life insurance business. If your policy offers guaranteed benefits, then these will be clearly marked “guaranteed’ in the illustration table on this page. If your policy offers variable benefits, then the illustrations on these pages will show two different rates of assumed future investment returns. Currently the gross investment returns are stipulated as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.
Unit Linked Life Insurance products are different from the traditional insurance products and are subject to the risk factors. Please know the associated risks and the applicable charges, from your Insurance Agent or Intermediary or Policy Document issued by the Insurance Company.
The fund is managed by Tata AIA Life Insurance Company Ltd. For more details on risk factors, terms and conditions please read Sales Brochure carefully before concluding a sale. The precise terms and condition of this plan are specified in the Policy Contract.
Past performance is not indicative of future performance. Returns are calculated on an absolute basis for a period of less than (or equal to) a year, with reinvestment of dividends (if any).
Various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns. Premium paid in Unit Linked Life Insurance policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the insured is responsible for his/her decisions
Investments are subject to market risks. The Company does not guarantee any assured returns. The investment income and price may go down as well as up depending on several factors influencing the market. Please make your own independent decision after consulting your financial or other professional advisor.
The fund is managed by Tata AIA Life Insurance Company Ltd. (hereinafter the “Company”). Tata AIA Life Insurance Company Limited is only the name of the Insurance Company & Tata AIA Smart Pension Secure is only the name of the Unit Linked Life Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns
The performance of the managed portfolios and funds is not guaranteed, and the value may increase or decrease in accordance with the future experience of the managed portfolios and funds.
The investment income and price may go down as well as up depending on several factors influencing the market. Please know the associated risks and the applicable charges, from your Insurance Agent or the Intermediary or Policy Document issued by the Insurance Company. Please make your own independent decision after consulting your financial or other professional advisor. Returns are calculated on an absolute basis for a period of less than (or equal to) a year, with reinvestment of dividends (if any). All investments made by the Company are subject to market risks. The Company does not guarantee any assured return.
The premium paid in Unit Linked Life Insurance policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the insured is responsible for his/her decisions. The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns. On survival to the end of the policy term, the Total Fund Value including Top-Up Premium Fund Value valued at applicable NAV on the date of Maturity will be paid
Life insurance cover is available under the solution. For details on products, associated risk factors, terms and conditions please read Sales Brochure carefully before concluding a sale.
L&C/Advt/2026/Sep/5306


 13.61% 5-yr returns1