







Call us
Call us
 FOR EXISTING POLICY
Have query on premium, payout or any servicing need?
Call us:
 FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY
Want to buy a new policy online?
FOR NEW POLICY (NRIs)
Note: Consent is provided to Tata AIA Life Insurance Company Limited to contact you by calling/giving missed call to the above numbers.
Thank you for sharing your details. To receive a call from Tata AIA Financial Advisor.
reCAPTCHA is not working.
No relevant search results found.
Popular searches
Continue from where you left of
A health insurance ULIP solution combines long-term wealth creation with life insurance, helping you work towards future financial goals... Read more while protecting your loved ones. Many individuals also consider a ULIP to prepare for rising healthcare costs over time. When supplemented with a critical illness rider, it can provide additional financial support if you are diagnosed with a covered critical illness. Read Less
ULIP Calculator
ULIP Calculator
Here’s your customised plan
Get Maturity Benefit
As per assumed rate of return
₹34.57 Lakh
As per assumed rate of return
₹34.57 Lakh
Total premium: ₹11.99 Lakh
Additional Benefits
Life Cover (including Terminal Illness Cover)
Accidental Death Cover
Accidental Total & Permanent Disability
Discount
Applicable if the policy is purchased digitally.
This discount is auto-applied and can't be removed
Tata AIA Premier SIP is a combination of the Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V01) and
Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V01). Both Tata AIA Smart SIP and Tata AIA Health Buddy are also available for sale individually. Product option: Future Secure.
Your premium calculation is in progress

Kindly enter the OTP sent to
Please enter valid OTP
01:60
Didn't receive OTP?
Technical issue detected
please continue without OTP verification
A unit linked health insurance plan is a solution that combines health-related financial protection with market-linked investment opportunities. Similar to a health insurance policy, it helps manage eligible medical expenses based on the policy terms. At the same time, a portion of the premium is invested in market-linked funds, allowing your investments the opportunity to grow over the long term.
Depending on the plan, you may choose from equity, debt, or balanced funds based on your financial goals and risk appetite. This dual approach enables a ULIP health insurance to support both long-term wealth creation and financial preparedness for future healthcare needs.
Here is how unit-linked health insurance plan work:
Insurers do not provide dedicated health-specific ULIP products. Policyholders can choose plans aligned with their investment timelines, existing financial capabilities, and projected medical funding needs.
Here is how ULIPs help with health-related expenses:
ULIP health benefits include life coverage ensuring family financial stability for medical bills, investment growth creating a healthcare corpus, flexible premium payments, and fund choices matching your financial situation. They also offer tax2 savings under Schedule I and II Income Tax Act, 2025
Let's understand how to choose the ULIP for health benefits:
The following are the key features and advantages of unit linked health plans:
ULIP plans can be useful for long-term healthcare planning because they combine life insurance with savings. Alongside life coverage, investors get access to market-linked investment opportunities. This helps build a savings fund for future medical requirements. Additionally, you have flexibility in investments and withdrawals after the lock-in period. Even though ULIP plans cannot replace healthcare insurance, they act as a supplementary financial resource.
1.
Yes, after five years, you can access accumulated wealth for urgent medical needs, though health insurance should remain primary emergency coverage.
2.
ULIPs create medical savings rather than providing treatment coverage; consider adding critical illness riders for specific disease financial protection.
3.
Yes, maturity funds generally have tax2 exemption under Schedule I, following premium limits and conditions defined in the Income Tax Act, 2025.
4.
Yes, many policies allow periodic fund reallocation, letting you switch investment strategies based on your needs and risk tolerance.
5.
If you pass away, death benefits provide your family with the necessary funds to manage medical bills, ongoing treatments, and expenses without financial burden.
The linked insurance product do not offer any liquidity during the first five years of the contract. The policy holder will not be able to surrender/withdraw the monies invested in linked insurance products completely or partially till the end of the fifth year.
Premier SIP is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Life Insurance Tata AIA Smart SIP - Non-participating, Unit-linked, Individual Life Insurance Savings Plan (UIN: 110L174V02) and (2) Tata AIA Health Buddy - Non-participating, Non-Linked, Individual Health Product (UIN:110N183V02). Product option: Future Secure These products are also available for sale individually without the combination offered/suggested.
Param Raksha Life Pro+ is designed for combination of Benefits of two individual and separate products named (1) Tata AIA Smart Sampoorna Raksha Supreme Unit Linked, Non-Participating Individual Life Insurance Plan (UIN: 110L179V02) and (2) Tata AIA Health Buddy, Non-Participating, Non-Linked, Individual Health Product (UIN: 110N183V02). These products are also available for sale individually without the combination offered/suggested
2Income Tax benefits would be available as per the prevailing income tax laws under old tax regime, subject to fulfilment of conditions stipulated therein. Income Tax laws are subject to change from time to time. Tata AIA Life Insurance Company Ltd. does not assume responsibility on tax implications mentioned anywhere on this site. Please consult your own tax consultant to know the tax benefits available to you.
3All funds open for new business which have completed 5 years since inception are rated 4 star or 5 star by Morningstar as of August 2025.
©2025 Morningstar. All rights reserved. The Morningstar name is a registered trademark of Morningstar, Inc. in India and other jurisdictions. The information contained here: (1) includes the proprietary information of Morningstar, Inc. and its affiliates, including, without limitation, Morningstar India Private Limited (“Morningstar”); (2) may not be copied, redistributed or used, by any means, in whole or in part, without the prior, written consent of Morningstar; (3) is not warranted to be complete, accurate or timely; and (4) may be drawn from data published on various dates and procured from various sources and (5) shall not be construed as an offer to buy or sell any security or other investment vehicle. Neither Morningstar, Inc. nor any of its affiliates (including, without limitation, Morningstar) nor any of their officers, directors, employees, associates or agents shall be responsible or liable for any trading decisions, damages or other losses resulting directly or indirectly from the information.
4Market-linked returns are subject to market risks and terms & conditions of the product. The assumed rate of returns or illustrated amount may not be guaranteed and depends on market fluctuations.
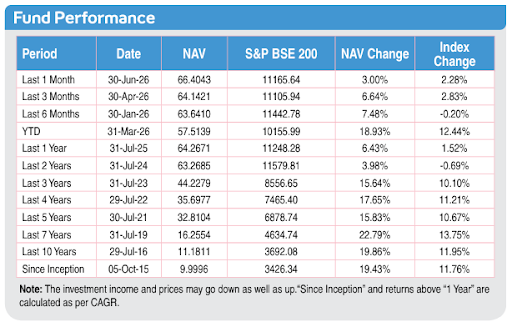
5Data from our TATA AIA fund factsheet shows the performance of TATA AIA Multi Cap fund & ULIF 060 15/07/14 MCF 110 as of July 2026. Benchmark of this fund is S&P BSE 200 – 100%.
Some benefits are guaranteed, and some benefits are variable with returns based on the future performance of your insurer carrying on life insurance business. If your policy offers guaranteed benefits, then these will be clearly marked “guaranteed’ in the illustration table on this page. If your policy offers variable benefits, then the illustrations on these pages will show two different rates of assumed future investment returns. Currently the gross investment returns are stipulated as 4% p.a. and 8% p.a. These assumed rates of return are not guaranteed, and these are not the upper or lower limits of what you might get back, as the value of your policy is dependent on a number of factors including actual future investment performance.
The fund is managed by Tata AIA Life Insurance Company Ltd. (hereinafter the "Company"). Tata AIA Life Insurance Company Limited is only the name of the Insurance Company & Tata AIA Smart SIP is only the name of the Unit Linked Life Insurance contract and does not in any way indicate the quality of the contract, its future prospects or returns.
Buying a Life Insurance policy is a long-term commitment. An early termination of the policy usually involves high costs, and the Surrender Value payable may be less than the all the Premiums Paid.
Life Insurance cover is available under the product. For more details on risk factors, terms and conditions please read sales brochure carefully before concluding a sale.
L&C/Advt/2026/Sep/5299


 Multi Cap Fund delivered 15.83% Returns (Benchmark: 10.67%)5